Company Coverage
Dialog Group (DLG MK): 1QFY27: Upstream Volumes Still Down; Looking Forward To 2Q
BUY (Maintained)
Current price:
Target price:
Upside:
RM1.87
RM2.95
+57.8%
Analyst
Highlights
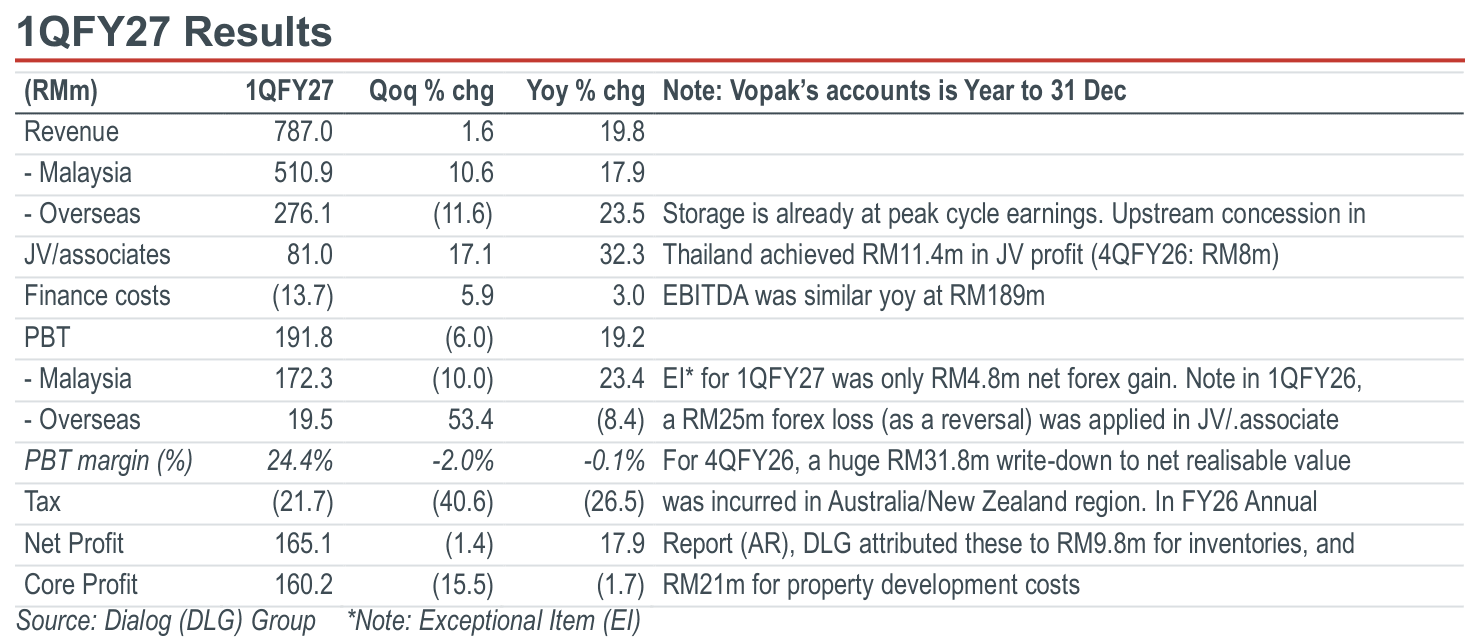
- 1QFY27 results were in line with our expectations. Although we do not have confirmed details of the segmental earnings mix, we believe upstream earnings were lacklustre considering the positive volatility in oil prices. This was because the maintenance activity for a Production Sharing Contract (PSC) remains in place since 3QFY26. We also believe earnings from the producing Cendramas PSC have not been recognised in 1QFY27.
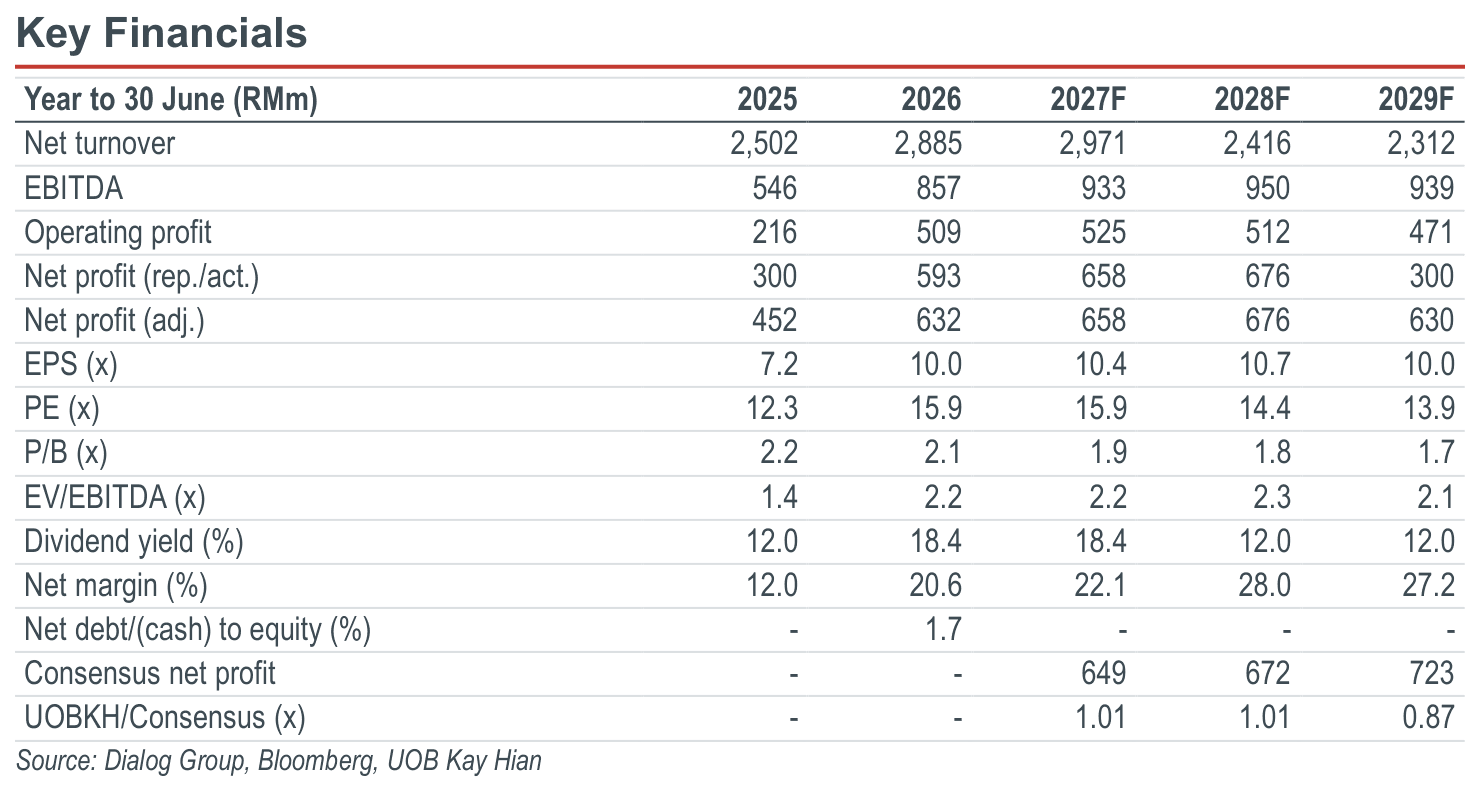
- 2QFY27 will be the quarter to look out for. As expected and highlighted by Royal Vopak, the storage earnings are flattish qoq as the midstream segment is at peak cycle earnings, but it will be sustainable. While we retain our forecasts, we anticipate the debut of Cendramas and Baram Junior Cluster (BJC; which had early first gas production) PSCs in upcoming 2QFY27 results. Maintain BUY with a target price of RM2.95.
Analysis
- 1QFY27 profit in line with market expectation, comprising 24%/25% of ours/consensus forecast. We make several assumptions, pending detailed guidance on segmental performance, relative to Dialog Group’s (DLG) disclosure of a 25:50:25 earnings mix across upstream/midstream/downstream operations for FY26. Firstly, for the JV/associate income, we assume only the Thailand upstream JV business had substantial qoq gains due to higher realised oil prices. 1QFY27 Malaysian JV profit of RM70m was in line with normal quarterly run-rate (1QFY26: RM56m; this was before reversing a RM25m forex loss). The JV storage business performance is aligned to Royal Vopak’s 3Q26 EBITDA disclosure from its Asian JV tank terminals.
Highlights
- 1QFY27 results were in line with our expectations. Although we do not have confirmed details of the segmental earnings mix, we believe upstream earnings were lacklustre considering the positive volatility in oil prices. This was because the maintenance activity for a Production Sharing Contract (PSC) remains in place since 3QFY26. We also believe earnings from the producing Cendramas PSC have not been recognised in 1QFY27.
- 2QFY27 will be the quarter to look out for. As expected and highlighted by Royal Vopak, the storage earnings are flattish qoq as the midstream segment is at peak cycle earnings, but it will be sustainable. While we retain our forecasts, we anticipate the debut of Cendramas and Baram Junior Cluster (BJC; which had early first gas production) PSCs in upcoming 2QFY27 results. Maintain BUY with a target price of RM2.95.
Analysis
- 1QFY27 profit in line with market expectation, comprising 24%/25% of ours/consensus forecast. We make several assumptions, pending detailed guidance on segmental performance, relative to Dialog Group’s (DLG) disclosure of a 25:50:25 earnings mix across upstream/midstream/downstream operations for FY26. Firstly, for the JV/associate income, we assume only the Thailand upstream JV business had substantial qoq gains due to higher realised oil prices. 1QFY27 Malaysian JV profit of RM70m was in line with normal quarterly run-rate (1QFY26: RM56m; this was before reversing a RM25m forex loss). The JV storage business performance is aligned to Royal Vopak’s 3Q26 EBITDA disclosure from its Asian JV tank terminals.
BUY (Maintained)
Current price:
Target price:
Upside:
RM1.87
RM2.95
+57.8%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

18 Nov 2026
Mr D.I.Y. Group (M) (MRDIY MK): 9M26: Below Expectations As SSSG Slumps

30 Sept 2026
VS Industry (VSI MK): 4QFY26: Turning The Corner; Deep Value Beckons

18 Nov 2026
Solarvest Holdings (SOLAR MK): 2QFY27: Higher Earnings Base; Expect 2HFY27 To Be Strong
Our latest research

18 Nov 2026
99 Speed Mart Retail Holdings (99SMART MK): 9M26: Within Expectations; SSSG Remains Robust
18 Nov 2026
Mr D.I.Y. Group (M) (MRDIY MK): 9M26: Below Expectations As SSSG Slumps
18 Nov 2026