Company Coverage
KIP REIT (KIP MK): Reaping More From Existing Assets
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM0.865
RM1.11
28.3%
RM1.15
Analyst
Highlights
- KIP REIT’s focus will now be on organic growth, having achieved its AUM target of RM2.0b after the completion of KIPMall Setapak on 30 Sep 26.
- While historical rental reversions averaged about 5% under the previous owner, management sees scope for 20-25% higher rents for new tenants. Meanwhile, we gather that AEI for KIPMall Masai should generate higher ROI of 10% compared to that of KIPMasai at 6%.
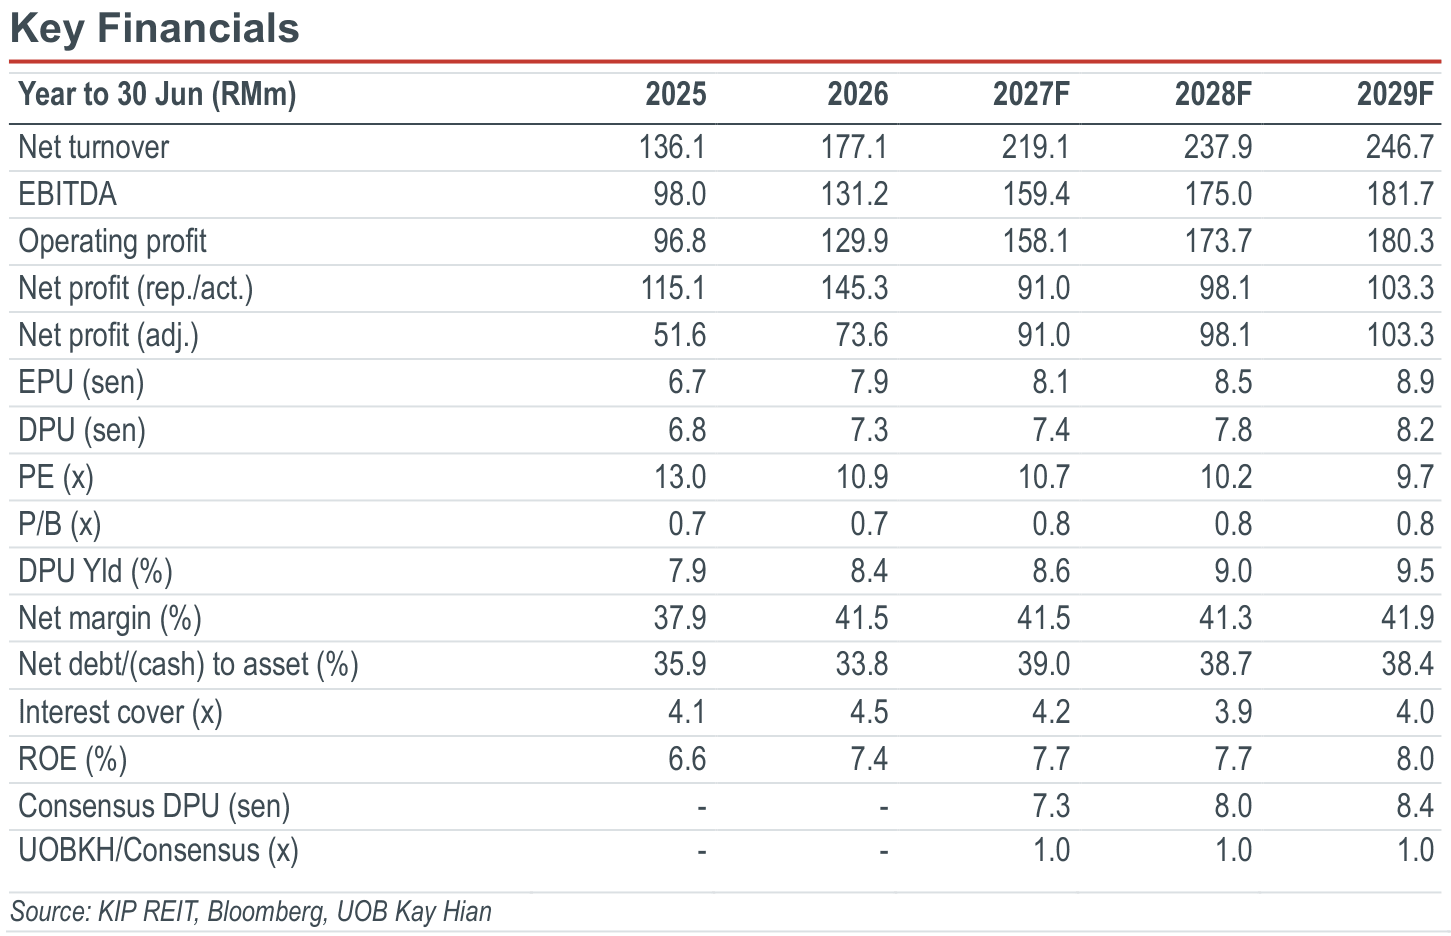
- Maintain BUY with a lower target price of RM1.11 as we increase our cost of equity assumption and rollover our valuation base to FY27. KIP REIT is one of our top picks, offering lush yields of 8.6% and 9.0% for FY27 and FY28.
Analysis
- Setapak’s NPI poised to exceed current run-rate. KIPMall Setapak’s annualised NPI run-rate stood at about RM36m as at end-Sep 26, already 15% above the RM31.3m disclosed in the acquisition circular for FY25. We expect NPI growth to be driven by rental reversions and cost efficiencies, with 20% and 50% of NLA expiring in 2027 and 2028, respectively. While historical rental reversions averaged around 5% under the previous owner, management sees scope for 20-25% higher rents for new tenants. We believe this is achievable, drawing confidence from its experience at D’Pulze Shopping Centre, where average rent rose 23% to RM6.18psf after one year of acquisition. Meanwhile, the consolidation of Setapak’s service contracts with the wider KIP REIT portfolio should generate cost savings.
- Anchor tenant replacement to enhance mall positioning. We view the introduction of Jaya Grocer, alongside Oriental Kopi and Panda Eyes, positively as it should enhance the mall’s tenant mix and potentially attract higher footfall. Jaya Grocer will replace Econsave on a 14% smaller footprint (24,395sf vs 28,295sf) under four successive three-year lease terms, while the remaining space will be leased to other two tenants. Combined rents from all three tenants are expected to be 42% higher than Econsave’s rent, which will add about 1% to the mall’s current NPI run-rate, per our estimate. Jaya Grocer is scheduled to open in 4QFY27, although management is targeting an earlier opening before Feb 27 (in 3QFY27).
Highlights
- KIP REIT’s focus will now be on organic growth, having achieved its AUM target of RM2.0b after the completion of KIPMall Setapak on 30 Sep 26.
- While historical rental reversions averaged about 5% under the previous owner, management sees scope for 20-25% higher rents for new tenants. Meanwhile, we gather that AEI for KIPMall Masai should generate higher ROI of 10% compared to that of KIPMasai at 6%.
- Maintain BUY with a lower target price of RM1.11 as we increase our cost of equity assumption and rollover our valuation base to FY27. KIP REIT is one of our top picks, offering lush yields of 8.6% and 9.0% for FY27 and FY28.
Analysis
- Setapak’s NPI poised to exceed current run-rate. KIPMall Setapak’s annualised NPI run-rate stood at about RM36m as at end-Sep 26, already 15% above the RM31.3m disclosed in the acquisition circular for FY25. We expect NPI growth to be driven by rental reversions and cost efficiencies, with 20% and 50% of NLA expiring in 2027 and 2028, respectively. While historical rental reversions averaged around 5% under the previous owner, management sees scope for 20-25% higher rents for new tenants. We believe this is achievable, drawing confidence from its experience at D’Pulze Shopping Centre, where average rent rose 23% to RM6.18psf after one year of acquisition. Meanwhile, the consolidation of Setapak’s service contracts with the wider KIP REIT portfolio should generate cost savings.
- Anchor tenant replacement to enhance mall positioning. We view the introduction of Jaya Grocer, alongside Oriental Kopi and Panda Eyes, positively as it should enhance the mall’s tenant mix and potentially attract higher footfall. Jaya Grocer will replace Econsave on a 14% smaller footprint (24,395sf vs 28,295sf) under four successive three-year lease terms, while the remaining space will be leased to other two tenants. Combined rents from all three tenants are expected to be 42% higher than Econsave’s rent, which will add about 1% to the mall’s current NPI run-rate, per our estimate. Jaya Grocer is scheduled to open in 4QFY27, although management is targeting an earlier opening before Feb 27 (in 3QFY27).
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM0.865
RM1.11
28.3%
RM1.15
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

8 Sept 2026
Property: 2Q26 Results Wrap-up

17 Sept 2026
CapitaLand Malaysia Trust (CLMT MK): Robust Enquiries For i-TechValley Assets

22 Oct 2026
CapitaLand Malaysia Trust (CLMT MK): 3Q26: Exceeds Expectations Due To Interest Cost Savings; Lush Dividend Yield Of 9-10%
Our latest research

29 Oct 2026
Bursa Malaysia (BURSA MK): 3Q26: Muted Near-term Outlook

29 Oct 2026
CTOS Digital (CTOS MK): 3Q26: Within Expectations; Trudging Across Choppy Seas

28 Oct 2026