Company Coverage
SP Setia (SPSB MK): 3Q26: Results Miss; Slower Execution Timelines Drag Earnings
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
RM0.605
RM0.600
-0.1%
RM1.060
Analyst
Highlights
- The results missed our expectations due to a weak performance from the property development segment.
- SP Setia has trimmed its 2026 launch target for the second consecutive quarter to RM3.99b amid softer residential demand, while pivoting towards industrial and commercial developments.
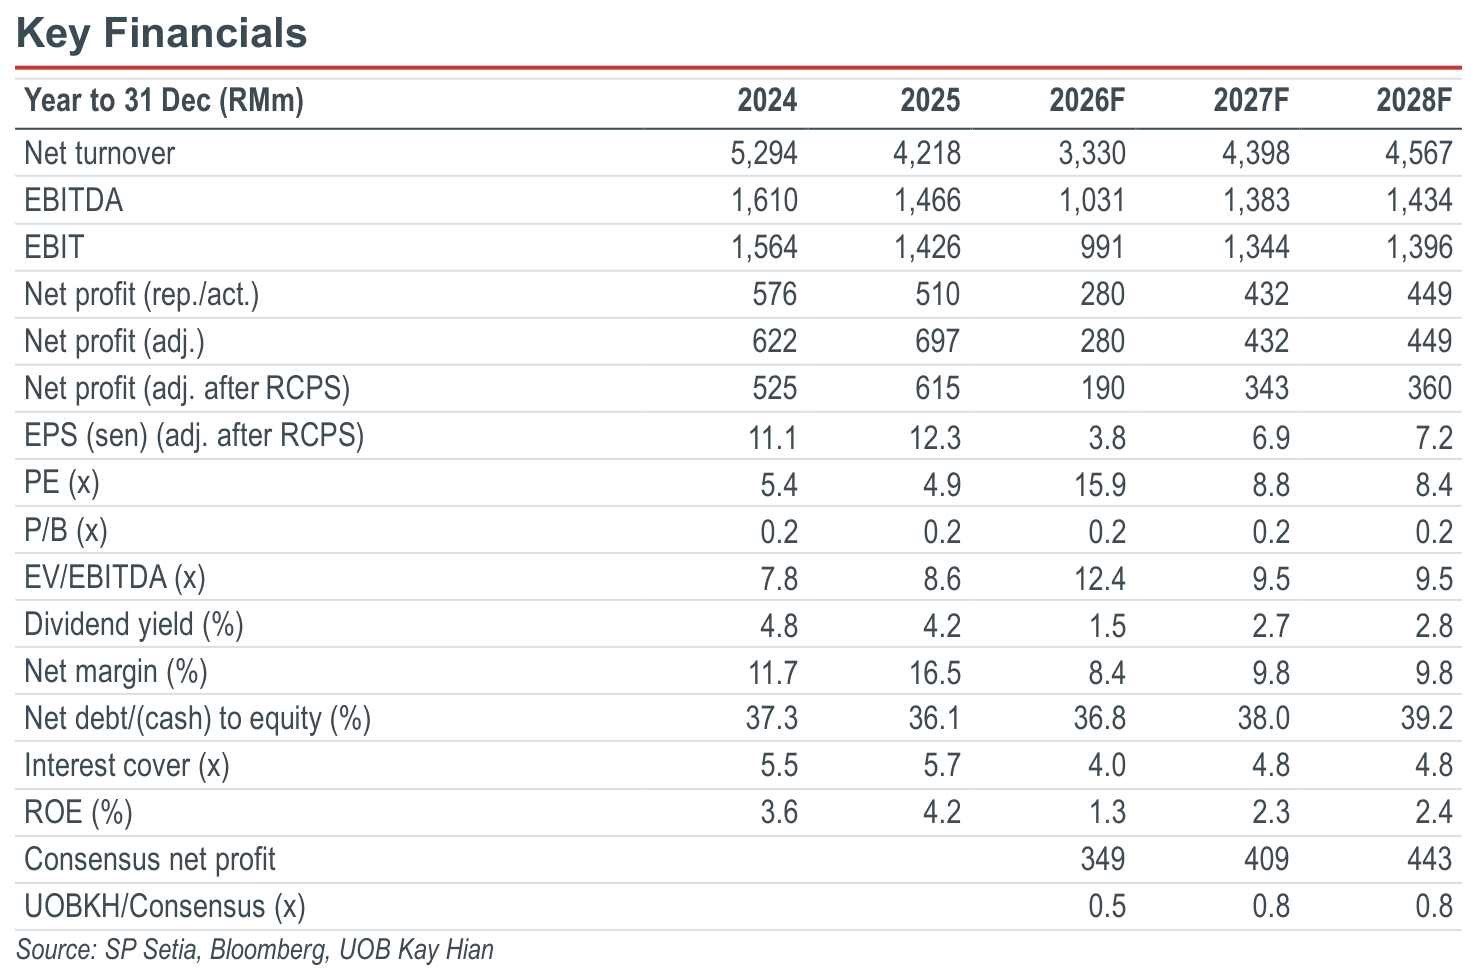
- Downgrade to HOLD with a lower target price of RM0.60 (from RM1.06), as we lift our discount to RNAV from 65% to 80% to reflect slower execution timelines, including its REIT listing that is now expected to happen in 3Q27.
Analysis
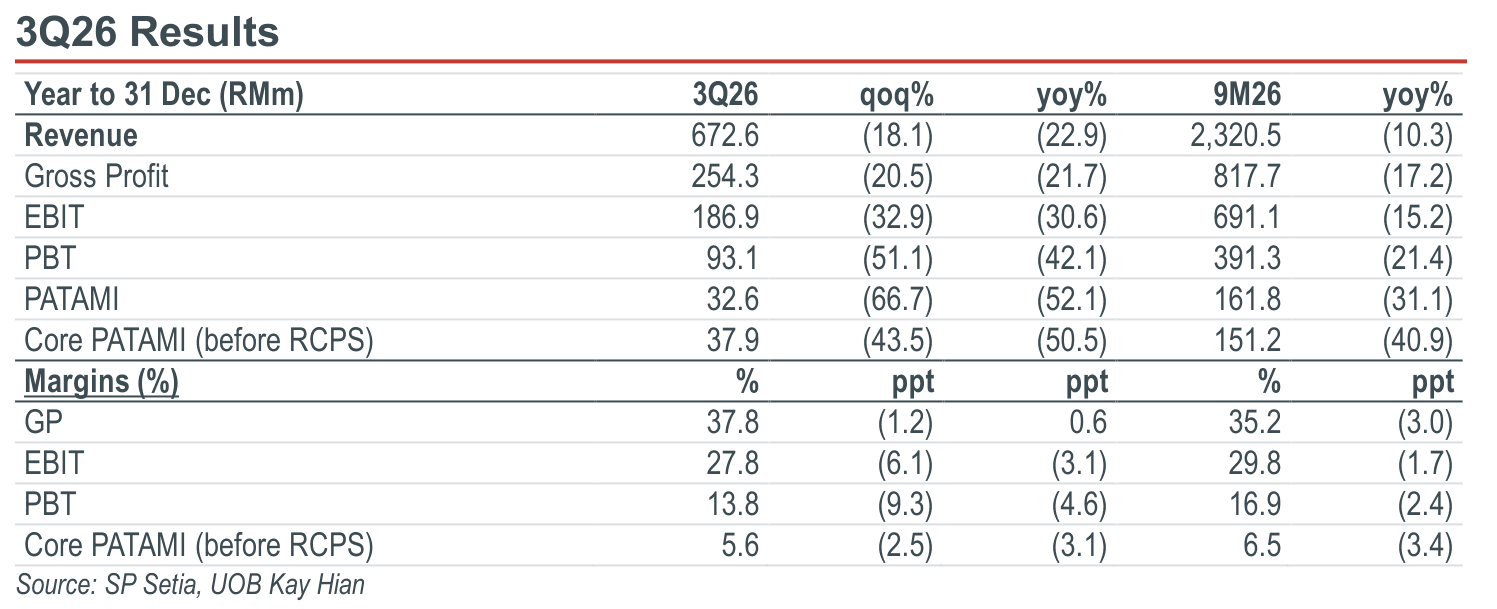
- Results miss. SP Setia’s 3Q26 core PATAMI was RM38m (-44% qoq, -51% yoy) on the back of RM672m in revenue (-18% qoq, -23% yoy). This brings 9M26 core PATAMI to RM151m (-41% yoy), accounting for 39%/46% of our and consensus full-year forecasts respectively. We attribute the results miss to its weak property development segment, including the slower-than-expected recognition of the Setia Alaman industrial land sales. As of end 3Q26, unbilled sales stood at RM3.9b (-1% qoq; -4% yoy).
Highlights
- The results missed our expectations due to a weak performance from the property development segment.
- SP Setia has trimmed its 2026 launch target for the second consecutive quarter to RM3.99b amid softer residential demand, while pivoting towards industrial and commercial developments.
- Downgrade to HOLD with a lower target price of RM0.60 (from RM1.06), as we lift our discount to RNAV from 65% to 80% to reflect slower execution timelines, including its REIT listing that is now expected to happen in 3Q27.
Analysis
- Results miss. SP Setia’s 3Q26 core PATAMI was RM38m (-44% qoq, -51% yoy) on the back of RM672m in revenue (-18% qoq, -23% yoy). This brings 9M26 core PATAMI to RM151m (-41% yoy), accounting for 39%/46% of our and consensus full-year forecasts respectively. We attribute the results miss to its weak property development segment, including the slower-than-expected recognition of the Setia Alaman industrial land sales. As of end 3Q26, unbilled sales stood at RM3.9b (-1% qoq; -4% yoy).
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
RM0.605
RM0.600
-0.1%
RM1.060
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Nov 2026
IGB REIT (IGBREIT MK) - 3Q26: In Line; Southkey Remains The Growth Engine

6 Nov 2026
Fraser & Neave Holdings (FNH MK) - FY26: Below Expectations; Setup Costs Remain A Drag

29 Oct 2026
CTOS Digital (CTOS MK): 3Q26: Within Expectations; Trudging Across Choppy Seas
Our latest research

12 Nov 2026
Heineken Malaysia (HEIM MK): 3Q26: Soft As Expected, Potentially Turning The Corner

11 Nov 2026
Sunway REIT (SREIT MK): 3Q26: In Line; Expect A Better 4Q26 On Seasonality

10 Nov 2026