Company Coverage
Sunway Construction (SCGB MK): 3Q26: Resilient Quarter WIthin Expectations
BUY (Maintained)
Current price:
Target price:
Upside:
RM7.50
RM8.44
4.5%
Analyst
Analyst
Highlights
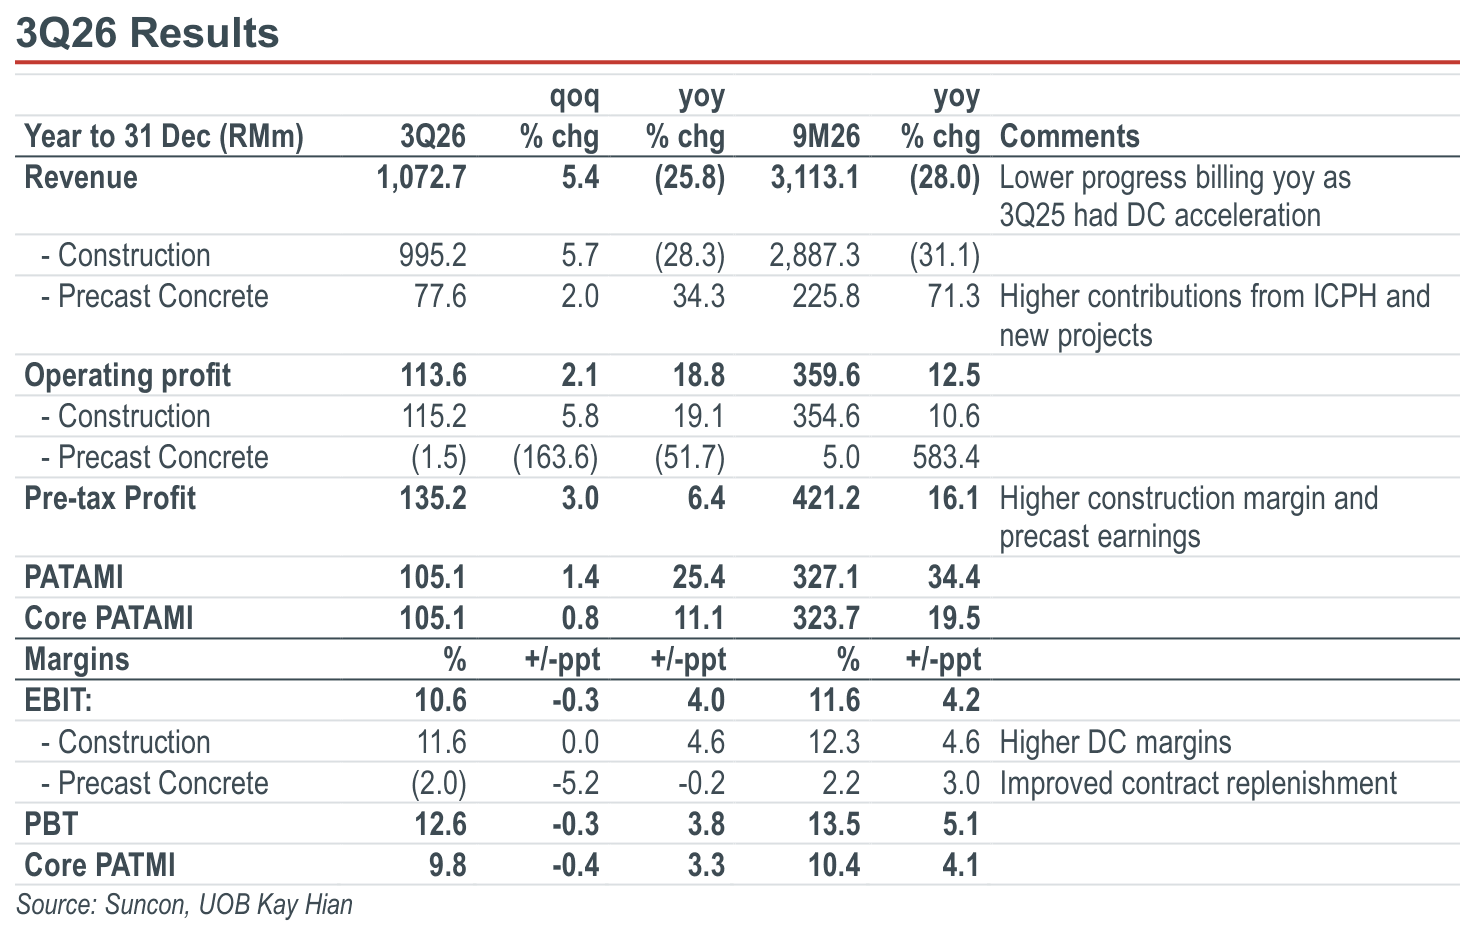
- 9M26 earnings were within expectations, making up 70% and 74% of our and consensus full-year estimates, respectively. Yoy growth was mainly driven by a favourable project mix which lifted blended margins.
- Declared interim dividend of 7.9 sen, bringing 9M26 dividend to 34.7 sen (9M25: 41.5sen) which implies a payout ratio of 141% and a yield of 4.6%.
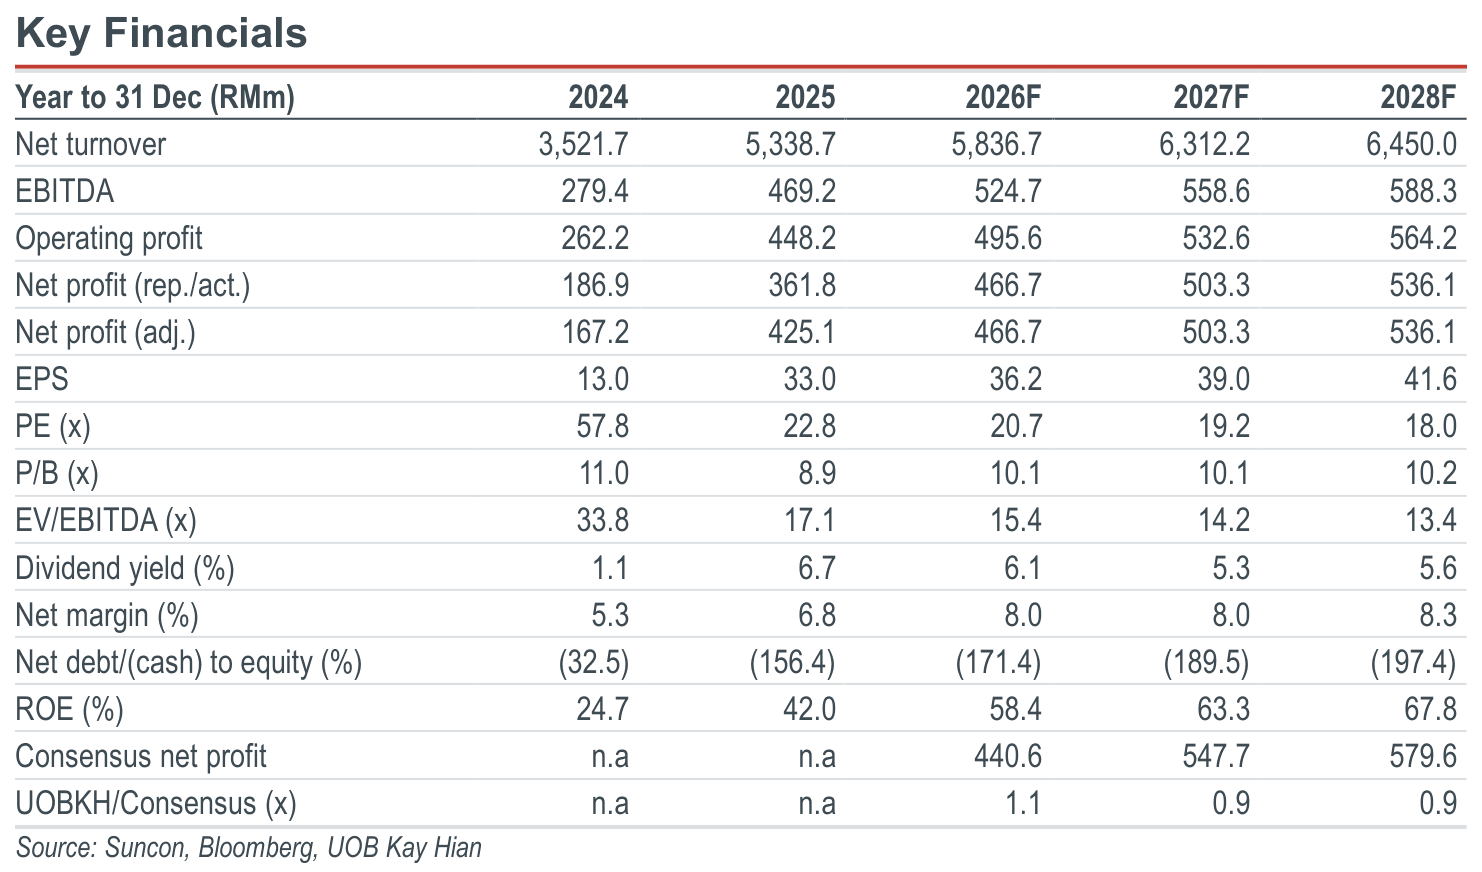
- Maintain BUY and target price of RM8.44, which implies 21.6x 2027F PE (+1SD above five-year mean of 18x).
Analysis
- 3Q26 results within expectations. Sunway Construction’s (Suncon) 3Q26 core net profit came in at RM105.1m (+1% qoq, +11% yoy), despite a lower revenue of RM1.07b (+5% qoq, -26% yoy). 9M26 earnings made up 70% and 74% of our and consensus full-year estimates respectively, and is deemed within expectations as we anticipate a seasonally stronger 4Q26.
Highlights
- 9M26 earnings were within expectations, making up 70% and 74% of our and consensus full-year estimates, respectively. Yoy growth was mainly driven by a favourable project mix which lifted blended margins.
- Declared interim dividend of 7.9 sen, bringing 9M26 dividend to 34.7 sen (9M25: 41.5sen) which implies a payout ratio of 141% and a yield of 4.6%.
- Maintain BUY and target price of RM8.44, which implies 21.6x 2027F PE (+1SD above five-year mean of 18x).
Analysis
- 3Q26 results within expectations. Sunway Construction’s (Suncon) 3Q26 core net profit came in at RM105.1m (+1% qoq, +11% yoy), despite a lower revenue of RM1.07b (+5% qoq, -26% yoy). 9M26 earnings made up 70% and 74% of our and consensus full-year estimates respectively, and is deemed within expectations as we anticipate a seasonally stronger 4Q26.
BUY (Maintained)
Current price:
Target price:
Upside:
RM7.50
RM8.44
4.5%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Sept 2026
Gamuda (GAM MK): 4QFY26: Setting The Foundations For A Strong FY27

19 Nov 2026
VSTECS (VST MK): 3Q26: Within expectations; Growth Momentum To Resume In 4Q26

20 Nov 2026
CelcomDigi (CDB MK): 3Q26: In Line; 2026 EBIT Guidance Revised Upwards
Our latest research
20 Nov 2026
CelcomDigi (CDB MK): 3Q26: In Line; 2026 EBIT Guidance Revised Upwards

19 Nov 2026
Inari Amertron (INRI MK): 1QFY27: Within Expectations; A Better FY27 In The Offing
19 Nov 2026