Company Coverage
Velesto Energy (VEB MK): Rig Market Getting Tighter
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM0.18
RM0.27
+48.9%
RM0.29
Analyst
Highlights
- Following our Aug 26 update, global rig outlook continues to see underlying bullishness on further rig tightening. This time, we observed that all rig segments from drillships and semisubs, to tender rigs and JU have enjoyed rising utilisation in recent months. 2027 outlook remains bullish, especially for the floaters and tender rigs. JU rigs share the same outlook but are blurred by timing complication of the Saudi Aramco situation. For Velesto Energy, channel checks indicate that Naga 3 (N3) secured a short-term contract in 4Q26 as expected. Hence, utilisation will increase from 56% in 2Q26 to about 95% by year-end. DCR is not likely to trend further down, despite potential new entry of an Indian JU rig.
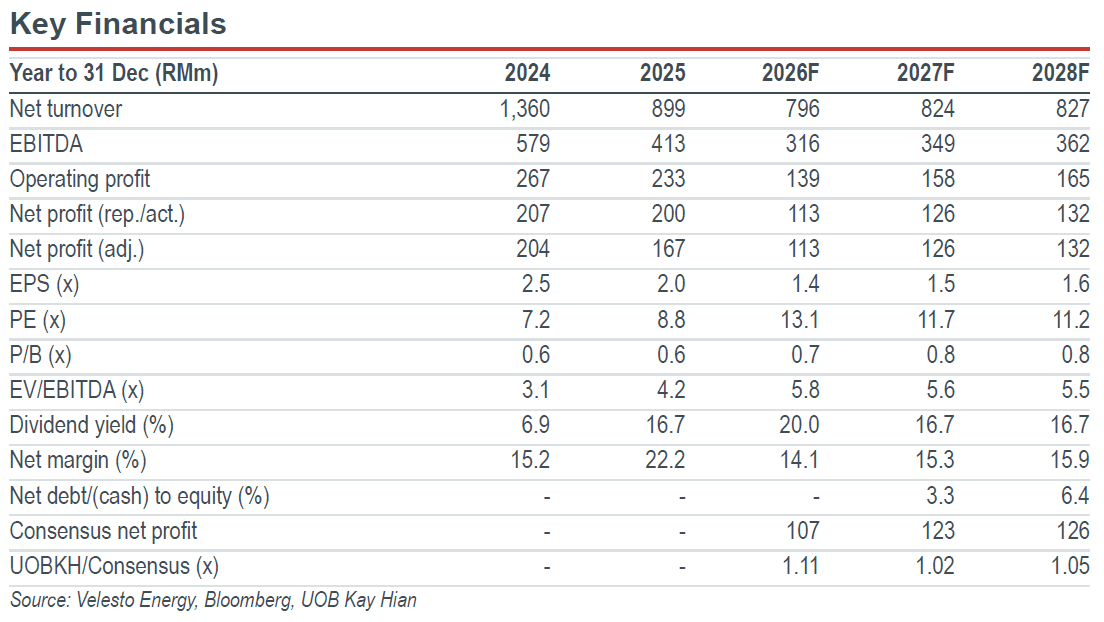
- VEB is now trading in tandem with global JU rig asset-based valuation, but far cheaper vs other listed peers. Despite cutting EBITDA/ DPS forecasts, VEB’s share price (trading at 5x EV/EBITDA) ignores its execution track record and dividend. On the contrary, global listed peers are trading at multi-cycle highs of 7-14x EV/EBITDA. Our alternative asset-based valuation shows VEB is now trading exactly the same as a JU rig value in recent M&A transactions. Maintain BUY with a lower target price of RM0.27.
Analysis
- Update: Naga 3 (N3) secured work from Oct 26. Our channel checks revealed that N3 secured a short-term drilling contract to be deployed offshore Sabah. Note that a short-term contract such as this may not require Velesto Energy (VEB) to issue a public announcement. However, based on VEB’s Aug 26 rig schedule, N3 had likely begun mobilisation from Labuan in mid-Oct 26 and may work all the way until Jan 27. We understand the rig continues to be marketed, and the priority is to bid for several potential jobs in the 2027/2028 horizon. In the meantime, with N3 getting a successful charter, VEB’s group utilisation may rebound from 56% in 2Q26 to almost 95% by 4Q26.
- N3 is still open as a potential sales candidate, although we believe VEB will not settle for any offer to sell for less than US$63m. Firstly, N3 had a complete refresh with the upgrade and maintenance exercise in 1H26, allowing its specifications to be as good as its competition. Secondly, recent M&A transaction multiples imply a jackup (JU) rig value of US$58m, which is a 5% increase since the Iranian conflict in Mar 26. This also aligns with the “rig security” theme that we predicted in our earlier reports.
Highlights
- Following our Aug 26 update, global rig outlook continues to see underlying bullishness on further rig tightening. This time, we observed that all rig segments from drillships and semisubs, to tender rigs and JU have enjoyed rising utilisation in recent months. 2027 outlook remains bullish, especially for the floaters and tender rigs. JU rigs share the same outlook but are blurred by timing complication of the Saudi Aramco situation. For Velesto Energy, channel checks indicate that Naga 3 (N3) secured a short-term contract in 4Q26 as expected. Hence, utilisation will increase from 56% in 2Q26 to about 95% by year-end. DCR is not likely to trend further down, despite potential new entry of an Indian JU rig.
- VEB is now trading in tandem with global JU rig asset-based valuation, but far cheaper vs other listed peers. Despite cutting EBITDA/ DPS forecasts, VEB’s share price (trading at 5x EV/EBITDA) ignores its execution track record and dividend. On the contrary, global listed peers are trading at multi-cycle highs of 7-14x EV/EBITDA. Our alternative asset-based valuation shows VEB is now trading exactly the same as a JU rig value in recent M&A transactions. Maintain BUY with a lower target price of RM0.27.
Analysis
- Update: Naga 3 (N3) secured work from Oct 26. Our channel checks revealed that N3 secured a short-term drilling contract to be deployed offshore Sabah. Note that a short-term contract such as this may not require Velesto Energy (VEB) to issue a public announcement. However, based on VEB’s Aug 26 rig schedule, N3 had likely begun mobilisation from Labuan in mid-Oct 26 and may work all the way until Jan 27. We understand the rig continues to be marketed, and the priority is to bid for several potential jobs in the 2027/2028 horizon. In the meantime, with N3 getting a successful charter, VEB’s group utilisation may rebound from 56% in 2Q26 to almost 95% by 4Q26.
- N3 is still open as a potential sales candidate, although we believe VEB will not settle for any offer to sell for less than US$63m. Firstly, N3 had a complete refresh with the upgrade and maintenance exercise in 1H26, allowing its specifications to be as good as its competition. Secondly, recent M&A transaction multiples imply a jackup (JU) rig value of US$58m, which is a 5% increase since the Iranian conflict in Mar 26. This also aligns with the “rig security” theme that we predicted in our earlier reports.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM0.18
RM0.27
+48.9%
RM0.29
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

27 Oct 2026
Gas Malaysia (GMB MK): Beneficiary Of Malaysia’s NG Supply Reform

29 Oct 2026
Bursa Malaysia (BURSA MK): 3Q26: Muted Near-term Outlook

26 Oct 2026
PPB Group (PEP MK): Resilient Wilmar Contributions Support Overall Performance
Our latest research

2 Nov 2026
IGB REIT (IGBREIT MK) - 3Q26: In Line; Southkey Remains The Growth Engine

2 Nov 2026
Pekat Group (PEKAT MK): Riding The CRESS Wave Into The Next Growth Chapter

2 Nov 2026