Periodic/Sector reports
Plantation: Stocks Hit A Record As Output Peaks
Highlights
- MPOB's Sep 26 data showed a 24.5% mom rise in Malaysia's palm oil stocks to a record 3.51m tonnes, above our 3.3m-tonne estimate. Production (2.12m tonnes) set a monthly record, while exports (1.12m tonnes) fell less than cargo surveyors had implied.
- We expect stocks to peak in October-November as India restocks after its duty cut, and to ease from December as output turns seasonally lower.
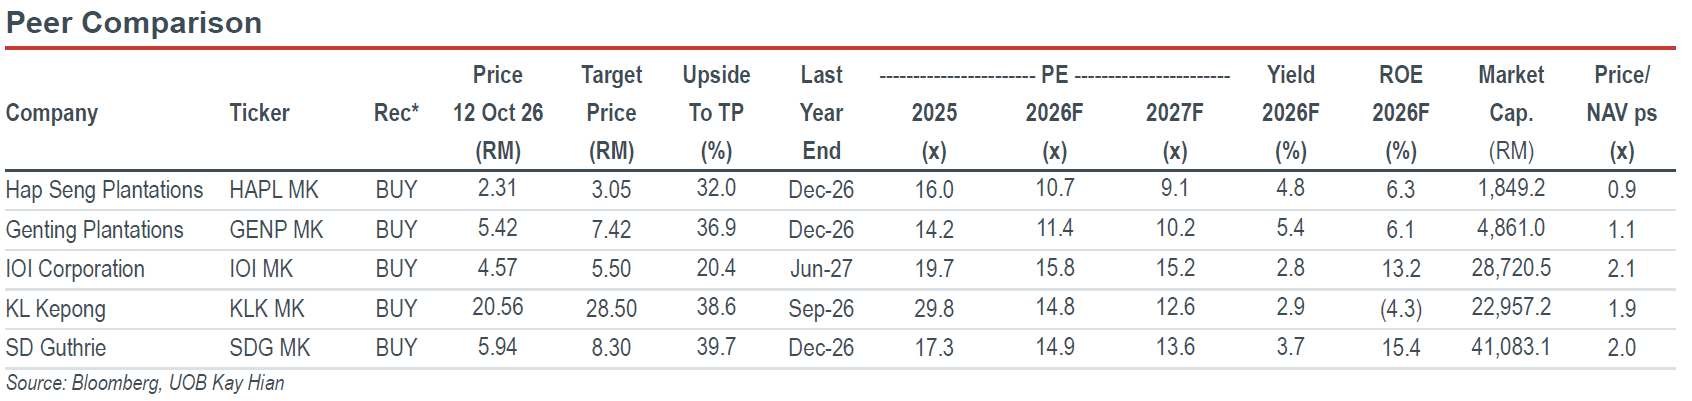
- Maintain OVERWEIGHT. Sector picks: SD Guthrie (BUY/Target: RM8.30), Genting Plantations (BUY/Target: RM7.42) and KL Kepong (BUY/Target: RM28.50).
Analysis
- MPOB's Sep 26 data. Palm oil inventory rose 24.5% mom to 3.51m tonnes, a sixth straight build and a record high, surpassing the 3.22m tonnes of Dec 18. The 692,000-tonne increase is the largest monthly build in MPOB's series, and the stock/usage ratio grew to 2.37x from 1.68x. Our call for stocks to test 3m tonnes by end-September proved too conservative.
- Production rose 16.5% mom to 2.12m tonnes, the highest monthly output on record (+15.0% yoy), though below the 21-25% mom rise in our survey. Sabah led (+35.0% mom), ahead of Sarawak (+15.5%) and Peninsular Malaysia (+10.9%). The national oil extraction rate increased 0.25ppt mom to 20.26%. 9M26 output of 14.75m tonnes was up 1.9% yoy.
- Exports fell 12.1% mom to 1.12m tonnes, the lowest since Apr 25, though shallower than the 17.1% mom drop in Intertek Testing Services estimates. Crude palm oil exports expanded 24.5% mom while processed palm oil declined 22.0%. Biodiesel exports dropped to 2,930 tonnes (-91.7% mom). 9M26 exports of 11.54m tonnes remained 4.6% ahead yoy.
- Imports went up 17.2% mom to 58,064 tonnes, including 6,812 tonnes of crude palm oil. Implied domestic disappearance fell 9.5% mom to 362,784 tonnes. With output below the Malaysian Palm Oil Association's estimate of about 19% growth and exports beating surveyors, weaker domestic offtake explains most of the overshoot against our stock estimate.
- Outlook. We expect stocks to peak in October-November and ease from December. India's cut in its crude palm oil duty to 11.0% from 16.5% on 24 September, and festive buying ahead of Diwali on 8 November, should support palm oil demand. ITS estimates 1-10 October exports rose 33.5% mom. Output should turn seasonally lower from November, and Malaysian Plantation and Commodities Minister Noraini Ahmad’s 19.5m-19.8m-tonne 2026 target implies only 1.58m-1.68m tonnes a month in 4Q26.
Highlights
- MPOB's Sep 26 data showed a 24.5% mom rise in Malaysia's palm oil stocks to a record 3.51m tonnes, above our 3.3m-tonne estimate. Production (2.12m tonnes) set a monthly record, while exports (1.12m tonnes) fell less than cargo surveyors had implied.
- We expect stocks to peak in October-November as India restocks after its duty cut, and to ease from December as output turns seasonally lower.
- Maintain OVERWEIGHT. Sector picks: SD Guthrie (BUY/Target: RM8.30), Genting Plantations (BUY/Target: RM7.42) and KL Kepong (BUY/Target: RM28.50).
Analysis
- MPOB's Sep 26 data. Palm oil inventory rose 24.5% mom to 3.51m tonnes, a sixth straight build and a record high, surpassing the 3.22m tonnes of Dec 18. The 692,000-tonne increase is the largest monthly build in MPOB's series, and the stock/usage ratio grew to 2.37x from 1.68x. Our call for stocks to test 3m tonnes by end-September proved too conservative.
- Production rose 16.5% mom to 2.12m tonnes, the highest monthly output on record (+15.0% yoy), though below the 21-25% mom rise in our survey. Sabah led (+35.0% mom), ahead of Sarawak (+15.5%) and Peninsular Malaysia (+10.9%). The national oil extraction rate increased 0.25ppt mom to 20.26%. 9M26 output of 14.75m tonnes was up 1.9% yoy.
- Exports fell 12.1% mom to 1.12m tonnes, the lowest since Apr 25, though shallower than the 17.1% mom drop in Intertek Testing Services estimates. Crude palm oil exports expanded 24.5% mom while processed palm oil declined 22.0%. Biodiesel exports dropped to 2,930 tonnes (-91.7% mom). 9M26 exports of 11.54m tonnes remained 4.6% ahead yoy.
- Imports went up 17.2% mom to 58,064 tonnes, including 6,812 tonnes of crude palm oil. Implied domestic disappearance fell 9.5% mom to 362,784 tonnes. With output below the Malaysian Palm Oil Association's estimate of about 19% growth and exports beating surveyors, weaker domestic offtake explains most of the overshoot against our stock estimate.
- Outlook. We expect stocks to peak in October-November and ease from December. India's cut in its crude palm oil duty to 11.0% from 16.5% on 24 September, and festive buying ahead of Diwali on 8 November, should support palm oil demand. ITS estimates 1-10 October exports rose 33.5% mom. Output should turn seasonally lower from November, and Malaysian Plantation and Commodities Minister Noraini Ahmad’s 19.5m-19.8m-tonne 2026 target implies only 1.58m-1.68m tonnes a month in 4Q26.
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

11 Sept 2026
Plantation: Fifth Straight Build As Exports Retreat

8 Oct 2026
Plantation: India's Duty Cut: Palm To Rebound Amid The Festive Window

10 Sept 2026
Plantation: EUDR Update: Key Facts Before December Implementation
Our latest research

14 Oct 2026
Construction: Budget 2027 Neutral; Marginal Lift From Expansionary Stance

14 Oct 2026
Renewable Energy: 18 sen/kwh SAC For CRESS Acceleration Programme, 3GW Of CRESS In The Pipeline
8 Oct 2026