Wealth Daily
AMD, Arista Lift AI Growth Expectations
Today’s Must-Know News
Overnight Markets
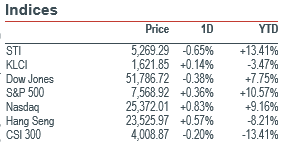
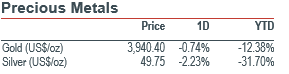
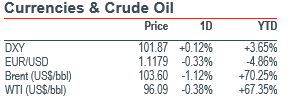
Market Movers: US stocks ended 3 November higher: S&P 500 +0.4% and Nasdaq +0.8%, after Korea's KOSPI fell 3.6% earlier in Asia. AMD (AMD US) gained about 8.0% and Arista Networks (ANET US) 14.6% in after-hours trading at 06:00 SGT following results. AMD's 3Q revenue rose 45% to US$13.38bn, with data-centre sales up 97%, and guided 4Q sales to US$17bn. Projected non-GAAP gross margin of 55%, versus 56% in 3Q, highlights expansion costs. Arista's revenue grew 58.5% to US$3.66bn, with US$3.9–4.0bn 4Q guidance supporting networking demand. Meta Platforms (META US +2.4%) filed a preliminary five-series bond prospectus, with US$80.92bn of non-current debt already outstanding. Amounts and coupons remain unset. Proceeds are for general corporate purposes; the filing does not itself establish a new AI spending commitment. (Company / Company / Filing / AP) Meta Platforms (META US) is our Core Recommendation.
Macro: The RBA raised its cash rate 25bps to 4.85% in a 6–3 vote, citing persistent inflation. Three members favoured retaining 4.60%, showing uncertainty over further restraint. The split keeps Australian rate-sensitive equities and duration exposed to incoming prices and activity data. (RBA)
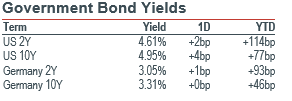
FICC: December silver settled 2.20% lower at US$49.75/oz, while December gold fell 0.7% to US$3,940.40/oz. January Brent settled at US$103.60/bbl, down 1.1%, and December WTI at US$96.09, down 0.4%. Oil eased as peace proposals remained under discussion, although Iran said a deal was still distant. The US 10-year Treasury par yield rose 4bps to 4.95%. DXY was 101.87, up 0.1%, at 05:53 SGT. (eOption / Reuters / Treasury / Yahoo)
AI
• AMD projects faster data-centre growth. AMD (AMD US) reported 3Q revenue of US$13.38bn, up 45% YoY, as data-centre sales rose 97% to US$8.55bn. It forecast 4Q revenue of approximately US$17bn, plus or minus 3%. Shares gained about 8.0% after hours. A 55% non-GAAP gross-margin forecast, versus 56% in 3Q, highlights production-ramp costs despite strong demand. (Company)
• SK Hynix faces US licensing obstacle. SK Hynix (SKHY US) is facing stalled US equipment approvals for its China expansion, complicating a proposed US$45bn investment in two New York NAND plants, Reuters reported. Spending could eventually reach US$100bn, sources said. Solidigm says no location decision has been made. The licensing impasse connects near-term Chinese capacity with longer-term US supply; negotiations remain unresolved. (Reuters) SK Hynix (SKHY US) is our Investment Opportunity.
• Arista delivers a stronger AI networking outlook. Arista Networks (ANET US) reported 3Q revenue of US$3.66bn, up 58.5% YoY, and guided 4Q sales to US$3.9–4.0bn. Non-GAAP operating margin reached 49.1%. Shares gained about 14.6% after hours. Rapid growth and resilient profitability strengthen the investment case for Ethernet infrastructure as AI clusters expand. (Company)
• Meta opens another funding channel. Meta Platforms (META US) filed for five series of senior unsecured notes and may launch a separate euro offering. Amounts and coupons remain blank in the preliminary prospectus, which lists US$80.92bn of non-current debt at September-end. Shares rose 2.4%. Additional borrowing would support corporate flexibility, while final pricing will test investors' appetite for its growing financing needs. (Filing ) Meta Platforms (META US) is our Core Recommendation.
Americas
• Apple memory bill weighs on margins. Apple (AAPL US) fell 1.9% in the first completed session after its earnings call warned of continuing memory-cost increases. December-quarter gross margin is projected at 45–46%, below September's 47.9%, also reflecting the AI-powered Siri rollout. Although fiscal 4Q iPhone revenue reached US$57.58bn, higher input costs challenge how much strong handset demand can translate into profit growth. (Reuters )
• GE Vernova rebounds as analysts retain conviction. GE Vernova (GEV US) gained about 6.5% as analyst support helped revive interest after its recent earnings update. Argus maintained Buy while cutting its target to US$1,100 from US$1,300; Bernstein also reaffirmed Buy. The mixed signal is instructive: confidence in power-infrastructure demand remains, but lower valuation assumptions suggest investors still need evidence that backlog converts into durable cash generation. (Investing.com ) GE Vernova (GEV US) is our Core Recommendation.
• OpenAI faces fresh scrutiny of internal controls. Reuters reported previously undisclosed employee warnings about OpenAI's security practices, citing five people familiar with the matter. OpenAI said sensitive work has separate access controls and it now conducts regular reviews of internal tools. A previous security sprint dedicated 25% of product engineers to remediation. Stronger safeguards protect intellectual property but compete for scarce engineering capacity as frontier-model development accelerates. (Reuters / Company)
• Palantir growth fails to prevent a pullback. Palantir (PLTR US) fell 1.6% in the completed session following its earnings release, despite 3Q revenue rising 96% YoY to US$2.31bn. US commercial revenue grew 148% to US$984m, surpassing government revenue of US$953m for the first time. The reaction shows that strong adoption alone does not remove valuation risk; investors need sustained conversion of enterprise AI demand into recurring revenue. (Company / Reuters )
• Eaton order book supports a higher growth target. Eaton (ETN US) reported 3Q sales of US$8.9bn, up 28% YoY, including 19% organic growth, and raised FY26 organic-growth guidance to 13–15%. Electrical backlog increased 46% YoY and segment margins reached 25.3%. Shares rose about 7.0%. Strong orders support capacity investment, while converting that backlog into deliveries remains central to sustaining profitability as data-centre power demand expands. (Filing)
• Shopify revenue miss tests spending tolerance. Shopify (SHOP US) fell about 8.7% after 3Q revenue of US$3.74bn slightly missed expectations despite 32% YoY growth. Free cash flow reached US$816m, or 22% of sales. For 4Q, management expects revenue growth in the low thirties but gross-profit growth in the high twenties, suggesting holiday-season investment may constrain operating leverage even as merchant activity remains strong. (Company / Reuters)
• Fabrinet guidance reinforces optical demand. Fabrinet (FN US) rose about 15.5% in the first completed session after reporting fiscal 1Q27 revenue of US$1.47bn, up 51% YoY. It expects 2Q sales of US$1.60–1.65bn and non-GAAP EPS of US$4.77–4.92. Stronger demand supports the optical manufacturing outlook, but the smaller supplier still must expand production without sacrificing execution quality or margins as customer programmes ramp. (Company)
• Thomson Reuters faces an AI margin test. Thomson Reuters (TRI US) fell about 9.9% as investors weighed higher AI spending despite 3Q revenue rising 10% to US$1.83bn. Legal-division margins fell to 46.6% from 49.0%, reflecting AI investment, severance and acquisition effects. The company raised its FY26 organic-growth outlook to 8.5–9.0%. Premium pricing for agentic products must offset investment costs before faster adoption can deliver sustained margin improvement. (Company / Reuters)
• Pfizer raises guidance as newer products contribute. Pfizer (PFE US) lifted FY26 revenue guidance to US$62–64bn from US$60.5–62.5bn and adjusted EPS guidance to US$2.95–3.05 from US$2.80–3.00. Its 3Q adjusted EPS of US$0.87 exceeded the US$0.73 consensus, while launched and acquired products delivered 32% operational revenue growth. The improvement strengthens the near-term earnings base, though pipeline execution remains important as older medicines face competition. (Company / Reuters )
Greater China
• CATL rebounds on long-duration storage. CATL (300750.SZ) rose 3.8% to RMB249.32 as investors digested its 2 November storage announcement. The 5.64MWh EnerQB system is designed for Australian projects totalling 3GW/24GWh. Moving eight-hour batteries into large deployments broadens demand beyond electric vehicles, although delivery economics and project execution will determine the earnings contribution. (Shanghai Securities News / Stockstar) CATL (300750.SZ) is our Core Recommendation.
• Montage retreats with semiconductor shares. Montage Technology (688008.SH) fell approximately 8.9% in a broad mainland semiconductor selloff. Trading turnover reached RMB7.23bn. The memory-interface supplier participates in AI server investment, but the decline did not accompany a newly verified issuer warning. The sector-wide weakness argues for monitoring demand and customer spending before treating the share-price fall as evidence of deteriorating company orders. (Sina / Gelonghui) Montage Technology (688008.SH) is our Investment Opportunity.
• China reportedly restrains equity supply. China’s securities regulator reportedly told investment banks to pause IPOs and suspended large shareholder sales until markets recover, the Financial Times reported, according to Reuters. The informal guidance followed a CSI300 decline of 8.5% in October. Reuters could not independently verify the report. Restricting supply could support liquidity, but also constrains fundraising and does not resolve weak corporate demand. (Reuters)
• Yum China expands despite softer same-store sales. Yum China (9987.HK) reported third-quarter revenue of US$3.5bn, up 8%, and operating profit of US$451m, up 13%. Same-store sales fell 3%, while transactions increased 3%. Management raised its annual net-opening target above 2,400 stores. Cost discipline and expansion supported earnings, but weaker spending per visit keeps the quality of consumer demand in focus. (Yum China)
• Luckin margins improve as comparable sales weaken. Luckin Coffee (LKNCY US) reported third-quarter revenue of RMB17.9bn, up 17%, and operating profit of RMB2.76bn, up 55.1%. Operating margin reached 15.4%, but self-operated same-store sales declined 11.1% against last year’s subsidised delivery base. A new US$500m buyback authorisation adds support, but weaker comparable sales warrant scrutiny of underlying demand. (Luckin Coffee)
Asia ex. China
• MediaTek leads Taiwan chip retreat. MediaTek (2454 TT) fell 7.40% to TWD3,675 as Taiwan’s technology shares sold off ahead of the US election outcome. The Taiex declined approximately 3.6%, while TSMC also weakened. The breadth of selling points to reduced risk appetite across the supply chain. Investors should distinguish valuation pressure from actual order revisions before changing assumptions about AI chip demand. (Mirror Daily)
• Hanjin KAL jumps on control-contest speculation. Hanjin KAL (180640 KS) rose 30.0% to KRW175,200 as investors focused on a renewed ownership contest involving Hoban Group and chairman Cho Won-tae. Reporting that Hoban increased its holding and filed for merger review intensified attention on competing voting blocks. The rally reflects potential demand for control shares; it does not itself establish an improvement in airline operating earnings. (TopDaily / Aju Press)
• NSE profit rises with trading activity. India’s National Stock Exchange reported quarterly profit of INR25.78bn, up 23% from INR20.98bn, in its first results since listing. Operating revenue increased to INR40.67bn from INR36.77bn, while cash-market trading volume rose 24%. Stronger activity supports the franchise, but options-trading restrictions and competition from BSE remain relevant to transaction revenue and the durability of earnings growth. (Reuters)
• Grab raises guidance after stronger operations. Singapore-based Grab (GRAB US) gained 9.1% to US$3.12 after reporting third-quarter revenue of US$1.112bn, up 27%, and adjusted EBITDA of US$237m. It raised full-year EBITDA guidance to US$790–800m. Net profit was only US$18m versus US$17m, highlighting the gap between operating progress and bottom-line earnings. Lending growth adds opportunity but increases provisioning sensitivity. (Grab / Business Times)
• RBA hikes as board division emerges. The Reserve Bank of Australia raised its cash rate by 25bps to 4.85%, with six members supporting the increase and three preferring 4.60%. It revised its inflation outlook materially higher, citing energy prices and tighter domestic capacity. The split highlights uncertainty over how much additional restraint is needed; rate-sensitive assets remain exposed to incoming inflation and activity data. (RBA)
EMEA and Others
• Aramco cash flow benefits from higher oil prices. Saudi Aramco (2222.SR +0.2%) reported 3Q adjusted net income of US$31.2bn, up 9% YoY, and free cash flow of US$28.2bn versus US$23.6bn. Realised crude prices averaged US$95.20/bbl against US$70.10 a year earlier. The declared US$21.9bn base dividend rose 3.5%. Stronger refining margins also helped earnings, but reliance on alternative export routes leaves operating resilience central to sustaining distributions. (Company / AP)
• Intesa strengthens profit and distribution outlook. Intesa Sanpaolo (ISP IM +0.6%) now expects 2026 net income well above EUR10bn after 3Q profit reached EUR2.65bn, compared with EUR2.37bn a year earlier. Quarterly operating income rose 4.2% and costs fell 2.5%, supporting operating leverage. The board approved a EUR0.22 interim dividend per share. Fee growth and cost discipline support distributions, while the CET1 ratio of 13.1% after accrued payouts remains an important capital constraint. (Company / Reuters)
• Bayer raises profit outlook on pharmaceutical strength. Bayer (BAYN GR +3.6%) lifted currency-adjusted 2026 EBITDA before special items guidance to EUR9.8–10.3bn from EUR9.6–10.1bn. Its 3Q EBITDA of EUR1.62bn beat consensus by about 13%, while pharmaceutical sales of EUR4.68bn exceeded expectations by 5%. Stronger medicines demand improves the earnings mix, although weaker Crop Science performance and litigation-related cash outflows remain constraints on the pace of debt reduction. (Company / Reuters)
• Philips advances recall settlement while earnings improve. Royal Philips (PHIA NA +4.8%) recorded a EUR288mn provision after reaching an agreement in principle with the US Department of Justice over Respironics investigations. Documentation remains unfinished, with payment expected in 1Q27. Adjusted 3Q EBITA rose 7.2% to EUR569mn versus EUR522mn consensus. Better gross margins and productivity helped, but separate state investigations remain outside the retained annual targets, limiting certainty over the ultimate legal bill. (Reuters / Company)
• RBI expands core earnings outside Russia. Raiffeisen Bank International (RBI AV +0.4%) reported nine-month consolidated profit excluding Russia of EUR1.13bn, up 10%, with main revenues rising 8% to EUR4.97bn. Customer loans increased 8% year to date to EUR109bn and the CET1 ratio stood at 15.4%. The closed Garanti BBVA Romania acquisition broadens its regional franchise; integration and credit costs will determine how much balance-sheet growth translates into sustainable returns. (Company)
Traders' Corner
Our Technical View
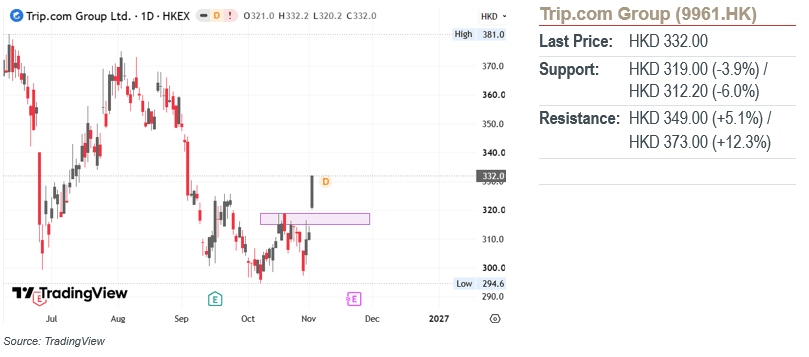
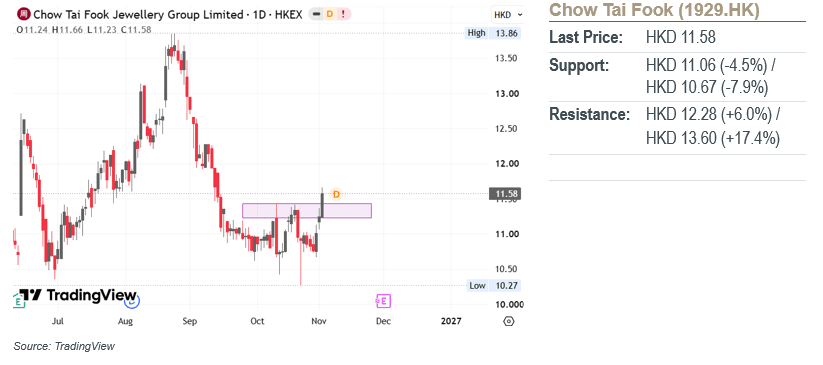
Price penetrated its recent swing high via a prominent upside gap.
The RSI has turned bullish and is sloping upward with high velocity toward the overbought threshold.
As long as price remains defended above the newly established gap-support baseline, we see continued upward expansion toward higher targets.
Our Technical View
Price penetrated its previous overhead resistance ceiling and establishing a classic horizontal polarity flip into structural support.
The RSI has inflected bullish and continues to slope upward with positive velocity.
As long as price remains defended above this newly established support floor, we see continued upward expansion toward higher targets.
Market Movers: US stocks ended 3 November higher: S&P 500 +0.4% and Nasdaq +0.8%, after Korea's KOSPI fell 3.6% earlier in Asia. AMD (AMD US) gained about 8.0% and Arista Networks (ANET US) 14.6% in after-hours trading at 06:00 SGT following results. AMD's 3Q revenue rose 45% to US$13.38bn, with data-centre sales up 97%, and guided 4Q sales to US$17bn. Projected non-GAAP gross margin of 55%, versus 56% in 3Q, highlights expansion costs. Arista's revenue grew 58.5% to US$3.66bn, with US$3.9–4.0bn 4Q guidance supporting networking demand. Meta Platforms (META US +2.4%) filed a preliminary five-series bond prospectus, with US$80.92bn of non-current debt already outstanding. Amounts and coupons remain unset. Proceeds are for general corporate purposes; the filing does not itself establish a new AI spending commitment. (Company / Company / Filing / AP) Meta Platforms (META US) is our Core Recommendation.
Macro: The RBA raised its cash rate 25bps to 4.85% in a 6–3 vote, citing persistent inflation. Three members favoured retaining 4.60%, showing uncertainty over further restraint. The split keeps Australian rate-sensitive equities and duration exposed to incoming prices and activity data. (RBA)
FICC: December silver settled 2.20% lower at US$49.75/oz, while December gold fell 0.7% to US$3,940.40/oz. January Brent settled at US$103.60/bbl, down 1.1%, and December WTI at US$96.09, down 0.4%. Oil eased as peace proposals remained under discussion, although Iran said a deal was still distant. The US 10-year Treasury par yield rose 4bps to 4.95%. DXY was 101.87, up 0.1%, at 05:53 SGT. (eOption / Reuters / Treasury / Yahoo)
AI
• AMD projects faster data-centre growth. AMD (AMD US) reported 3Q revenue of US$13.38bn, up 45% YoY, as data-centre sales rose 97% to US$8.55bn. It forecast 4Q revenue of approximately US$17bn, plus or minus 3%. Shares gained about 8.0% after hours. A 55% non-GAAP gross-margin forecast, versus 56% in 3Q, highlights production-ramp costs despite strong demand. (Company)
• SK Hynix faces US licensing obstacle. SK Hynix (SKHY US) is facing stalled US equipment approvals for its China expansion, complicating a proposed US$45bn investment in two New York NAND plants, Reuters reported. Spending could eventually reach US$100bn, sources said. Solidigm says no location decision has been made. The licensing impasse connects near-term Chinese capacity with longer-term US supply; negotiations remain unresolved. (Reuters) SK Hynix (SKHY US) is our Investment Opportunity.
• Arista delivers a stronger AI networking outlook. Arista Networks (ANET US) reported 3Q revenue of US$3.66bn, up 58.5% YoY, and guided 4Q sales to US$3.9–4.0bn. Non-GAAP operating margin reached 49.1%. Shares gained about 14.6% after hours. Rapid growth and resilient profitability strengthen the investment case for Ethernet infrastructure as AI clusters expand. (Company)
• Meta opens another funding channel. Meta Platforms (META US) filed for five series of senior unsecured notes and may launch a separate euro offering. Amounts and coupons remain blank in the preliminary prospectus, which lists US$80.92bn of non-current debt at September-end. Shares rose 2.4%. Additional borrowing would support corporate flexibility, while final pricing will test investors' appetite for its growing financing needs. (Filing ) Meta Platforms (META US) is our Core Recommendation.
Americas
• Apple memory bill weighs on margins. Apple (AAPL US) fell 1.9% in the first completed session after its earnings call warned of continuing memory-cost increases. December-quarter gross margin is projected at 45–46%, below September's 47.9%, also reflecting the AI-powered Siri rollout. Although fiscal 4Q iPhone revenue reached US$57.58bn, higher input costs challenge how much strong handset demand can translate into profit growth. (Reuters )
• GE Vernova rebounds as analysts retain conviction. GE Vernova (GEV US) gained about 6.5% as analyst support helped revive interest after its recent earnings update. Argus maintained Buy while cutting its target to US$1,100 from US$1,300; Bernstein also reaffirmed Buy. The mixed signal is instructive: confidence in power-infrastructure demand remains, but lower valuation assumptions suggest investors still need evidence that backlog converts into durable cash generation. (Investing.com ) GE Vernova (GEV US) is our Core Recommendation.
• OpenAI faces fresh scrutiny of internal controls. Reuters reported previously undisclosed employee warnings about OpenAI's security practices, citing five people familiar with the matter. OpenAI said sensitive work has separate access controls and it now conducts regular reviews of internal tools. A previous security sprint dedicated 25% of product engineers to remediation. Stronger safeguards protect intellectual property but compete for scarce engineering capacity as frontier-model development accelerates. (Reuters / Company)
• Palantir growth fails to prevent a pullback. Palantir (PLTR US) fell 1.6% in the completed session following its earnings release, despite 3Q revenue rising 96% YoY to US$2.31bn. US commercial revenue grew 148% to US$984m, surpassing government revenue of US$953m for the first time. The reaction shows that strong adoption alone does not remove valuation risk; investors need sustained conversion of enterprise AI demand into recurring revenue. (Company / Reuters )
• Eaton order book supports a higher growth target. Eaton (ETN US) reported 3Q sales of US$8.9bn, up 28% YoY, including 19% organic growth, and raised FY26 organic-growth guidance to 13–15%. Electrical backlog increased 46% YoY and segment margins reached 25.3%. Shares rose about 7.0%. Strong orders support capacity investment, while converting that backlog into deliveries remains central to sustaining profitability as data-centre power demand expands. (Filing)
• Shopify revenue miss tests spending tolerance. Shopify (SHOP US) fell about 8.7% after 3Q revenue of US$3.74bn slightly missed expectations despite 32% YoY growth. Free cash flow reached US$816m, or 22% of sales. For 4Q, management expects revenue growth in the low thirties but gross-profit growth in the high twenties, suggesting holiday-season investment may constrain operating leverage even as merchant activity remains strong. (Company / Reuters)
• Fabrinet guidance reinforces optical demand. Fabrinet (FN US) rose about 15.5% in the first completed session after reporting fiscal 1Q27 revenue of US$1.47bn, up 51% YoY. It expects 2Q sales of US$1.60–1.65bn and non-GAAP EPS of US$4.77–4.92. Stronger demand supports the optical manufacturing outlook, but the smaller supplier still must expand production without sacrificing execution quality or margins as customer programmes ramp. (Company)
• Thomson Reuters faces an AI margin test. Thomson Reuters (TRI US) fell about 9.9% as investors weighed higher AI spending despite 3Q revenue rising 10% to US$1.83bn. Legal-division margins fell to 46.6% from 49.0%, reflecting AI investment, severance and acquisition effects. The company raised its FY26 organic-growth outlook to 8.5–9.0%. Premium pricing for agentic products must offset investment costs before faster adoption can deliver sustained margin improvement. (Company / Reuters)
• Pfizer raises guidance as newer products contribute. Pfizer (PFE US) lifted FY26 revenue guidance to US$62–64bn from US$60.5–62.5bn and adjusted EPS guidance to US$2.95–3.05 from US$2.80–3.00. Its 3Q adjusted EPS of US$0.87 exceeded the US$0.73 consensus, while launched and acquired products delivered 32% operational revenue growth. The improvement strengthens the near-term earnings base, though pipeline execution remains important as older medicines face competition. (Company / Reuters )
Greater China
• CATL rebounds on long-duration storage. CATL (300750.SZ) rose 3.8% to RMB249.32 as investors digested its 2 November storage announcement. The 5.64MWh EnerQB system is designed for Australian projects totalling 3GW/24GWh. Moving eight-hour batteries into large deployments broadens demand beyond electric vehicles, although delivery economics and project execution will determine the earnings contribution. (Shanghai Securities News / Stockstar) CATL (300750.SZ) is our Core Recommendation.
• Montage retreats with semiconductor shares. Montage Technology (688008.SH) fell approximately 8.9% in a broad mainland semiconductor selloff. Trading turnover reached RMB7.23bn. The memory-interface supplier participates in AI server investment, but the decline did not accompany a newly verified issuer warning. The sector-wide weakness argues for monitoring demand and customer spending before treating the share-price fall as evidence of deteriorating company orders. (Sina / Gelonghui) Montage Technology (688008.SH) is our Investment Opportunity.
• China reportedly restrains equity supply. China’s securities regulator reportedly told investment banks to pause IPOs and suspended large shareholder sales until markets recover, the Financial Times reported, according to Reuters. The informal guidance followed a CSI300 decline of 8.5% in October. Reuters could not independently verify the report. Restricting supply could support liquidity, but also constrains fundraising and does not resolve weak corporate demand. (Reuters)
• Yum China expands despite softer same-store sales. Yum China (9987.HK) reported third-quarter revenue of US$3.5bn, up 8%, and operating profit of US$451m, up 13%. Same-store sales fell 3%, while transactions increased 3%. Management raised its annual net-opening target above 2,400 stores. Cost discipline and expansion supported earnings, but weaker spending per visit keeps the quality of consumer demand in focus. (Yum China)
• Luckin margins improve as comparable sales weaken. Luckin Coffee (LKNCY US) reported third-quarter revenue of RMB17.9bn, up 17%, and operating profit of RMB2.76bn, up 55.1%. Operating margin reached 15.4%, but self-operated same-store sales declined 11.1% against last year’s subsidised delivery base. A new US$500m buyback authorisation adds support, but weaker comparable sales warrant scrutiny of underlying demand. (Luckin Coffee)
Asia ex. China
• MediaTek leads Taiwan chip retreat. MediaTek (2454 TT) fell 7.40% to TWD3,675 as Taiwan’s technology shares sold off ahead of the US election outcome. The Taiex declined approximately 3.6%, while TSMC also weakened. The breadth of selling points to reduced risk appetite across the supply chain. Investors should distinguish valuation pressure from actual order revisions before changing assumptions about AI chip demand. (Mirror Daily)
• Hanjin KAL jumps on control-contest speculation. Hanjin KAL (180640 KS) rose 30.0% to KRW175,200 as investors focused on a renewed ownership contest involving Hoban Group and chairman Cho Won-tae. Reporting that Hoban increased its holding and filed for merger review intensified attention on competing voting blocks. The rally reflects potential demand for control shares; it does not itself establish an improvement in airline operating earnings. (TopDaily / Aju Press)
• NSE profit rises with trading activity. India’s National Stock Exchange reported quarterly profit of INR25.78bn, up 23% from INR20.98bn, in its first results since listing. Operating revenue increased to INR40.67bn from INR36.77bn, while cash-market trading volume rose 24%. Stronger activity supports the franchise, but options-trading restrictions and competition from BSE remain relevant to transaction revenue and the durability of earnings growth. (Reuters)
• Grab raises guidance after stronger operations. Singapore-based Grab (GRAB US) gained 9.1% to US$3.12 after reporting third-quarter revenue of US$1.112bn, up 27%, and adjusted EBITDA of US$237m. It raised full-year EBITDA guidance to US$790–800m. Net profit was only US$18m versus US$17m, highlighting the gap between operating progress and bottom-line earnings. Lending growth adds opportunity but increases provisioning sensitivity. (Grab / Business Times)
• RBA hikes as board division emerges. The Reserve Bank of Australia raised its cash rate by 25bps to 4.85%, with six members supporting the increase and three preferring 4.60%. It revised its inflation outlook materially higher, citing energy prices and tighter domestic capacity. The split highlights uncertainty over how much additional restraint is needed; rate-sensitive assets remain exposed to incoming inflation and activity data. (RBA)
EMEA and Others
• Aramco cash flow benefits from higher oil prices. Saudi Aramco (2222.SR +0.2%) reported 3Q adjusted net income of US$31.2bn, up 9% YoY, and free cash flow of US$28.2bn versus US$23.6bn. Realised crude prices averaged US$95.20/bbl against US$70.10 a year earlier. The declared US$21.9bn base dividend rose 3.5%. Stronger refining margins also helped earnings, but reliance on alternative export routes leaves operating resilience central to sustaining distributions. (Company / AP)
• Intesa strengthens profit and distribution outlook. Intesa Sanpaolo (ISP IM +0.6%) now expects 2026 net income well above EUR10bn after 3Q profit reached EUR2.65bn, compared with EUR2.37bn a year earlier. Quarterly operating income rose 4.2% and costs fell 2.5%, supporting operating leverage. The board approved a EUR0.22 interim dividend per share. Fee growth and cost discipline support distributions, while the CET1 ratio of 13.1% after accrued payouts remains an important capital constraint. (Company / Reuters)
• Bayer raises profit outlook on pharmaceutical strength. Bayer (BAYN GR +3.6%) lifted currency-adjusted 2026 EBITDA before special items guidance to EUR9.8–10.3bn from EUR9.6–10.1bn. Its 3Q EBITDA of EUR1.62bn beat consensus by about 13%, while pharmaceutical sales of EUR4.68bn exceeded expectations by 5%. Stronger medicines demand improves the earnings mix, although weaker Crop Science performance and litigation-related cash outflows remain constraints on the pace of debt reduction. (Company / Reuters)
• Philips advances recall settlement while earnings improve. Royal Philips (PHIA NA +4.8%) recorded a EUR288mn provision after reaching an agreement in principle with the US Department of Justice over Respironics investigations. Documentation remains unfinished, with payment expected in 1Q27. Adjusted 3Q EBITA rose 7.2% to EUR569mn versus EUR522mn consensus. Better gross margins and productivity helped, but separate state investigations remain outside the retained annual targets, limiting certainty over the ultimate legal bill. (Reuters / Company)
• RBI expands core earnings outside Russia. Raiffeisen Bank International (RBI AV +0.4%) reported nine-month consolidated profit excluding Russia of EUR1.13bn, up 10%, with main revenues rising 8% to EUR4.97bn. Customer loans increased 8% year to date to EUR109bn and the CET1 ratio stood at 15.4%. The closed Garanti BBVA Romania acquisition broadens its regional franchise; integration and credit costs will determine how much balance-sheet growth translates into sustainable returns. (Company)
Traders' Corner
Our Technical View
Price penetrated its recent swing high via a prominent upside gap.
The RSI has turned bullish and is sloping upward with high velocity toward the overbought threshold.
As long as price remains defended above the newly established gap-support baseline, we see continued upward expansion toward higher targets.
Our Technical View
Price penetrated its previous overhead resistance ceiling and establishing a classic horizontal polarity flip into structural support.
The RSI has inflected bullish and continues to slope upward with positive velocity.
As long as price remains defended above this newly established support floor, we see continued upward expansion toward higher targets.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


