Company Coverage
Affin Bank (ABANK MK): 3Q26: Robust Loan Growth Comes At A Cost
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM1.95
RM2.13
8.7%
RM2.48
Analyst
Highlights
- Higher impairments outweighed the double-digit income growth, driving an 8.7% decline in Affin’s 9M26 earnings and missing expectations.
- Management expects NIM to stabilise, but funding constraints and potential additional credit buffers temper the earnings outlook.
- Maintain HOLD as elevated credit costs continue to weigh on earnings prospects; lower target price to RM2.13 from RM2.48 following earnings cuts.
Analysis
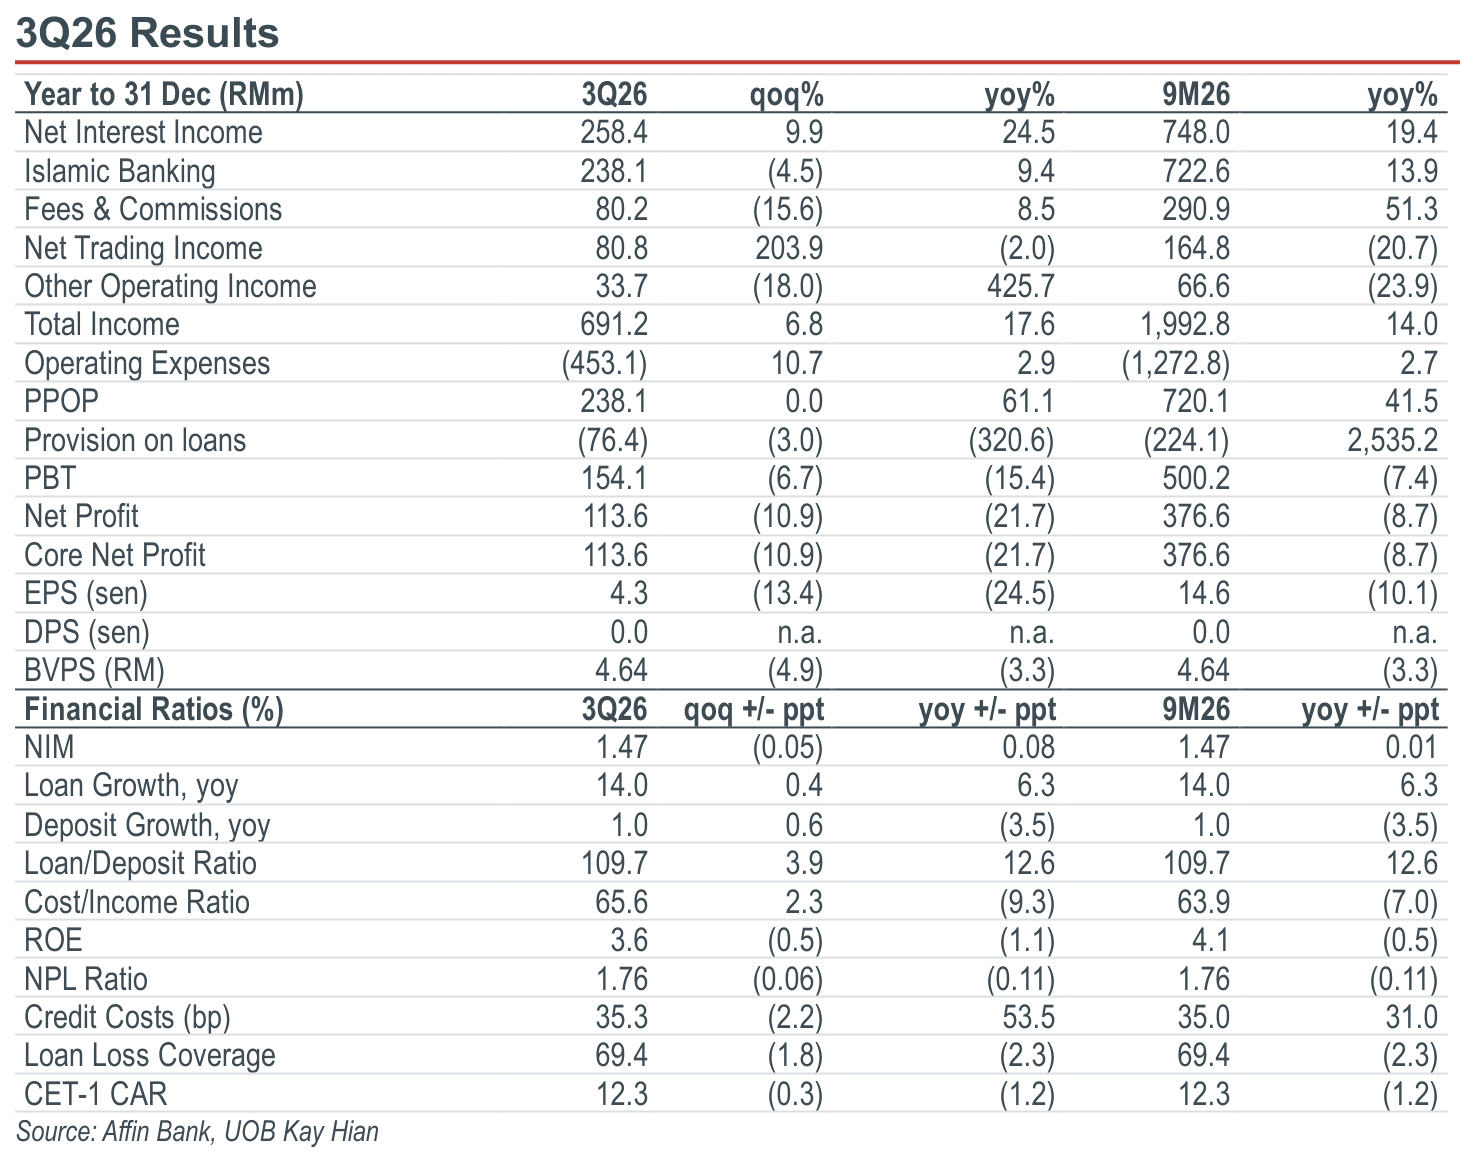
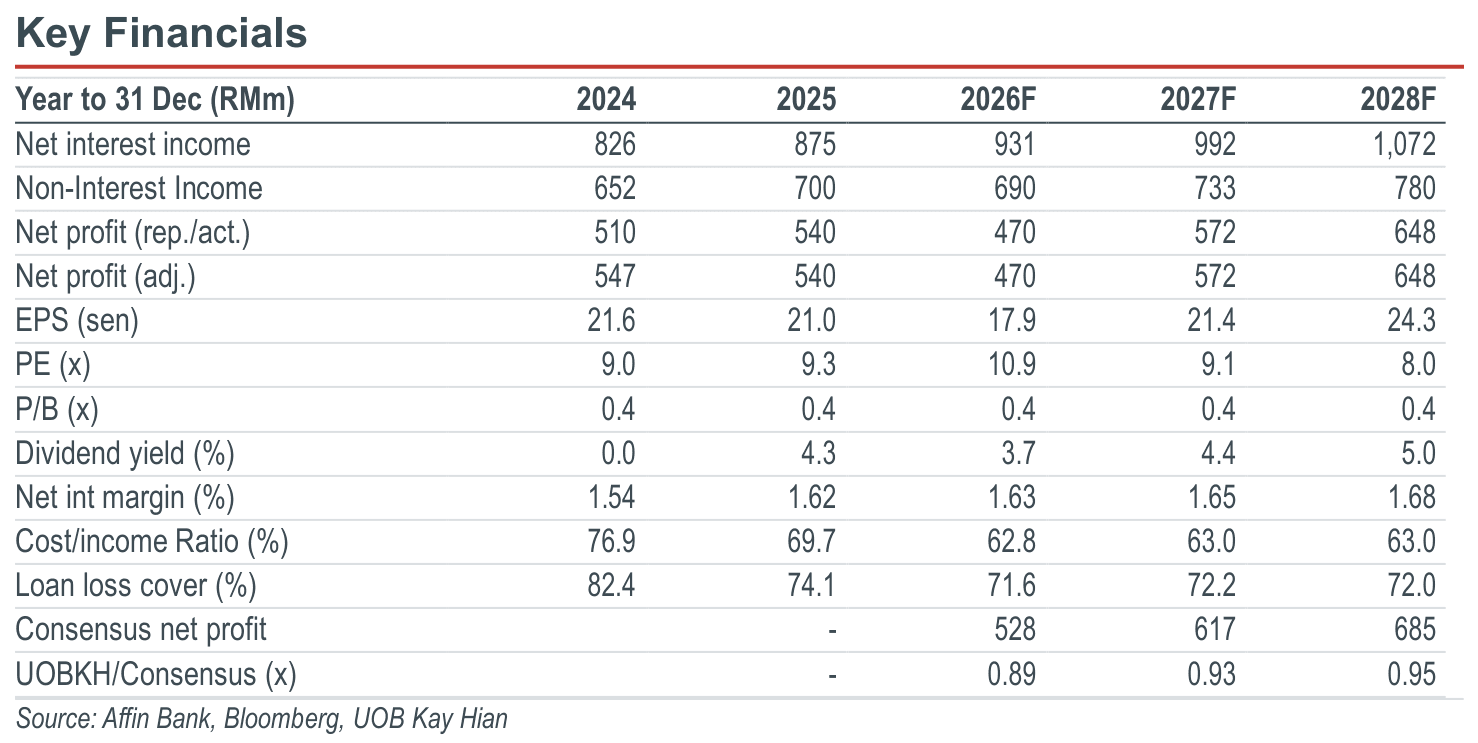
- Below expectations. Affin Bank (Affin) delivered 3Q26 net profit of RM113.6m (-21.7% yoy, -10.9% qoq), bringing 9M26 earnings to RM376.6m (-8.7% yoy). Earnings came in below expectations, with 9M26 earnings accounting for 68% and 71% of our and consensus full-year estimates, respectively. The shortfall reflected elevated impairment charges and higher operating expenses, which weighed on earnings despite continued income growth.
Highlights
- Higher impairments outweighed the double-digit income growth, driving an 8.7% decline in Affin’s 9M26 earnings and missing expectations.
- Management expects NIM to stabilise, but funding constraints and potential additional credit buffers temper the earnings outlook.
- Maintain HOLD as elevated credit costs continue to weigh on earnings prospects; lower target price to RM2.13 from RM2.48 following earnings cuts.
Analysis
- Below expectations. Affin Bank (Affin) delivered 3Q26 net profit of RM113.6m (-21.7% yoy, -10.9% qoq), bringing 9M26 earnings to RM376.6m (-8.7% yoy). Earnings came in below expectations, with 9M26 earnings accounting for 68% and 71% of our and consensus full-year estimates, respectively. The shortfall reflected elevated impairment charges and higher operating expenses, which weighed on earnings despite continued income growth.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM1.95
RM2.13
8.7%
RM2.48
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

29 Oct 2026
CTOS Digital (CTOS MK): 3Q26: Within Expectations; Trudging Across Choppy Seas

10 Nov 2026
Public Bank (PBK MK): 3Q26: Below Forecasts Due To NIM Pressure And Higher Credit Cost

2 Nov 2026
IGB REIT (IGBREIT MK) - 3Q26: In Line; Southkey Remains The Growth Engine
Our latest research

13 Nov 2026
Hartalega (HART MK): 2QFY27: Mounting Cost Pressures Earnings Outlook

12 Nov 2026
Heineken Malaysia (HEIM MK): 3Q26: Soft As Expected, Potentially Turning The Corner

12 Nov 2026