Company Coverage
HE Group (HEGROUP MK): A Diversified MEP Player; Scaling Up On DC And Semiconductor Demand
NOT RATED
Current price:
Target price:
Upside:
RM1.11
n.a.
n.a.
Analyst
Highlights
- HE’s orderbook reached a record RM441m following RM416m in ytd wins across seven projects, lifting orderbook coverage to 3.6x 2025 revenue and providing visibility through 1Q28.
- The RM1.6b tender book is around 60% DC-related, and Phase 1 incumbency positions HE for subsequent phases across six-phase campuses. Semiconductor capex upcycle and CRESS renewable projects offer further growth legs.
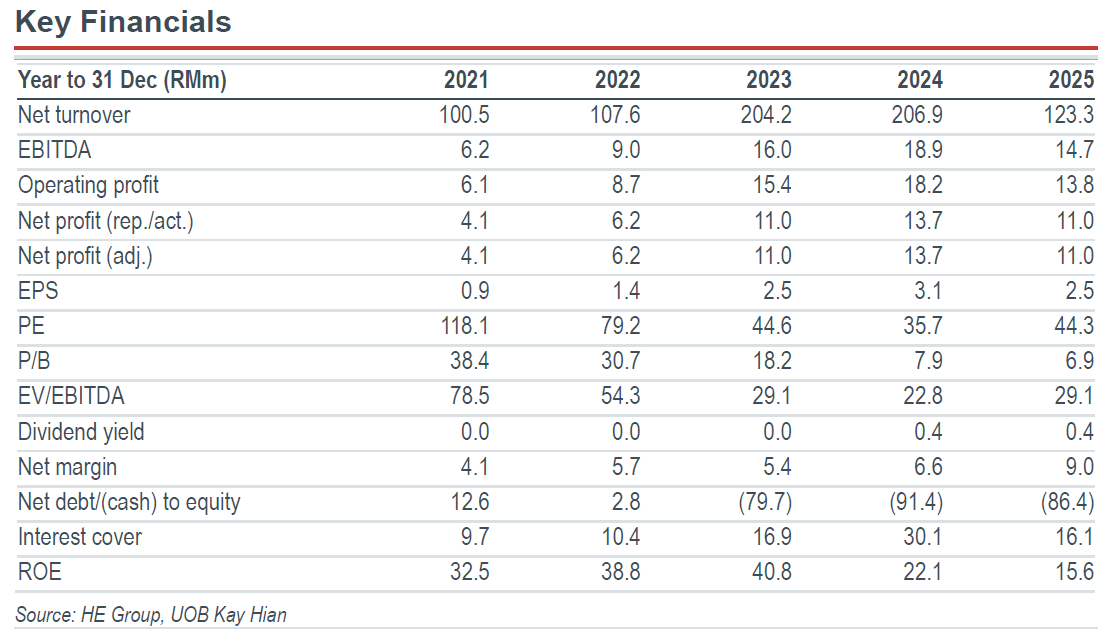
- Following a relatively quiet 2025, progressive billing on the orderbook should drive a 50-60% EPS growth to RM16m-18m in 2026. This implies 27-30x 2026F PE, broadly in line with peers.
Analysis
- Record orderbook... Following its largest-ever RM124m data centre (DC) contract win in 23 Sept, HE Group’s (HE) outstanding orderbook rose to RM441m, a new record high. Ytd contract wins have reached RM416m across seven projects, highlighting the rapid scale-up following the group’s strategic pivot towards DCs. 2025 was a relatively quiet year as HE repositioned the business, securing its maiden DC project in Cyberjaya before the two larger packages in Johor in 2026. The tender book remains sizeable at RM1.6b, with around 60% DC-related across six projects. Management remains positive on DC demand despite potential regulatory tightening, noting that the broader project pipeline remains intact.
- …provides visibility through 2028, with further campus phases offering upside. The current RM441m orderbook translates to 3.6x 2025 revenue cover, with contracted projects scheduled for completion by 1Q28. With more projects entering the progressive billing phase, management expects a sustained quarterly revenue run rate of RM50m-60m in 2H26; this implies an estimated 2026 revenue of RM180m-200m (1H26: RM72.4m). Importantly, current DC awards cover only the first phase of client campuses planned across six phases, with full build-out targeted by 2029 based on clients’ current plans. Phase 1 incumbency positions HE to secure subsequent phases, supporting continued orderbook replenishment and extending earnings visibility beyond the current project cycle.
Highlights
- HE’s orderbook reached a record RM441m following RM416m in ytd wins across seven projects, lifting orderbook coverage to 3.6x 2025 revenue and providing visibility through 1Q28.
- The RM1.6b tender book is around 60% DC-related, and Phase 1 incumbency positions HE for subsequent phases across six-phase campuses. Semiconductor capex upcycle and CRESS renewable projects offer further growth legs.
- Following a relatively quiet 2025, progressive billing on the orderbook should drive a 50-60% EPS growth to RM16m-18m in 2026. This implies 27-30x 2026F PE, broadly in line with peers.
Analysis
- Record orderbook... Following its largest-ever RM124m data centre (DC) contract win in 23 Sept, HE Group’s (HE) outstanding orderbook rose to RM441m, a new record high. Ytd contract wins have reached RM416m across seven projects, highlighting the rapid scale-up following the group’s strategic pivot towards DCs. 2025 was a relatively quiet year as HE repositioned the business, securing its maiden DC project in Cyberjaya before the two larger packages in Johor in 2026. The tender book remains sizeable at RM1.6b, with around 60% DC-related across six projects. Management remains positive on DC demand despite potential regulatory tightening, noting that the broader project pipeline remains intact.
- …provides visibility through 2028, with further campus phases offering upside. The current RM441m orderbook translates to 3.6x 2025 revenue cover, with contracted projects scheduled for completion by 1Q28. With more projects entering the progressive billing phase, management expects a sustained quarterly revenue run rate of RM50m-60m in 2H26; this implies an estimated 2026 revenue of RM180m-200m (1H26: RM72.4m). Importantly, current DC awards cover only the first phase of client campuses planned across six phases, with full build-out targeted by 2029 based on clients’ current plans. Phase 1 incumbency positions HE to secure subsequent phases, supporting continued orderbook replenishment and extending earnings visibility beyond the current project cycle.
NOT RATED
Current price:
Target price:
Upside:
RM1.11
n.a.
n.a.
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

24 Sept 2026
Sunway Construction (SCGB MK): Retracement Offers Opportunities; Upgrade To BUY

21 Sept 2026
Northern Solar (NORTHERN MK): All Cylinders Fired Up

10 Sept 2026
VSTECS (VST MK): AI Infrastructure Demand Broadens; Momentum Building Into 2H26
Our latest research

9 Oct 2026
Hume Cement Industries (HUME MK): Business Resilience Continues To Cement Its Margin Leadership

8 Oct 2026
Northern Solar (NORTHERN MK): Wins Another LSS5 EPCC Award; Underpins Earnings Visibility

7 Oct 2026