Company Coverage
Hume Cement Industries (HUME MK): Business Resilience Continues To Cement Its Margin Leadership
BUY (Maintained)
Current price:
Target price:
Upside:
RM2.57
RM4.16
+61.9%
Analyst
Highlights
- While bulk cement ASPs have modestly normalised from the Nov 25 price adjustments (<10%), HUME continues to demonstrate margin resilience.
- The group remains well-equipped to manage cost headwinds, underpinned by: a) its disciplined coal procurement strategy, b) ongoing operational efficiency initiatives, and c) an agile manufacturing mix.
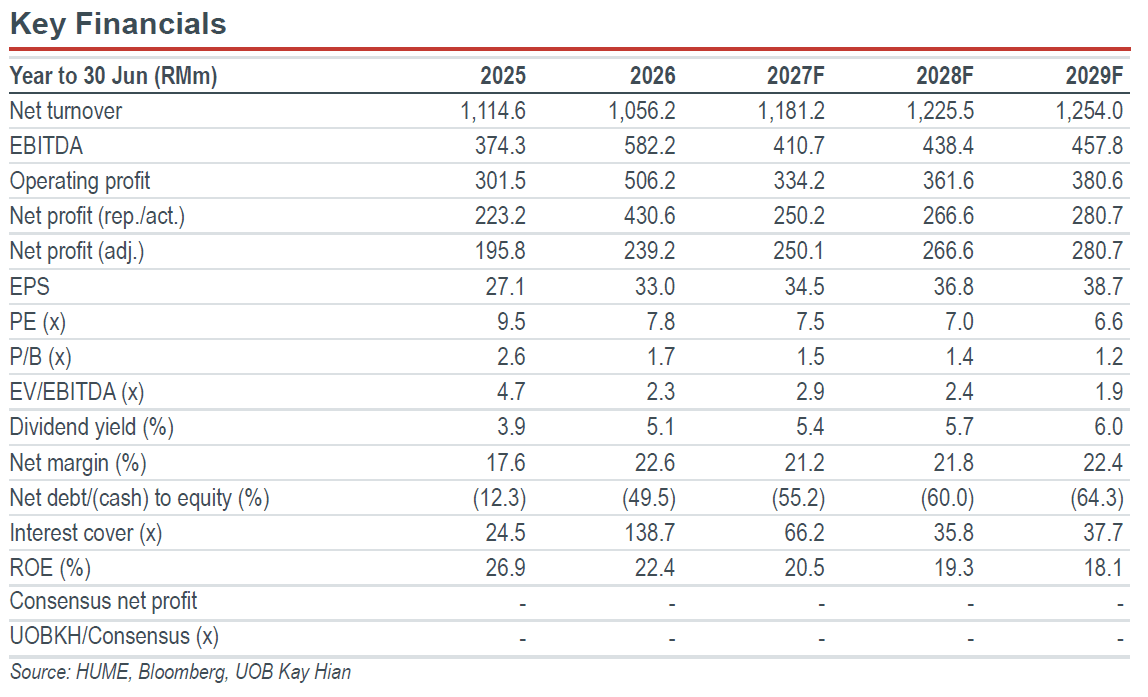
- HUME trades at an undemanding 7.5x FY27F PE (-1SD from industry mean), and offers attractive dividend yields of 5.4% and 5.7% over FY27-28. Maintain BUY with a target price of RM4.16.
Analysis
- Well-positioned to navigate elevated coal prices. The cement sector’s share prices have retraced by approximately 26% ytd, largely reflecting the sharp rise in Newcastle coal prices (+42% ytd) and Indonesian coal benchmark prices (+43% ytd). While coal typically represents a significant portion of Hume Cement Industries’ (HUME) COGS, the group remains well-equipped to manage cost headwinds, underpinned by: a) its disciplined coal procurement strategy; b) ongoing operational efficiency initiatives; and c) an agile manufacturing mix, prioritising production of high demand products.
- Solid coal procurement strategy. HUME's fuel cost resilience is underpinned by its advanced technology which enables utilisation of lower-grade coal without compromising product quality. The aforementioned coal generally trades at a discount to Newcastle benchmark coal, enabling the group to benefit from cost advantage. Coupled with HUME's strategy of accumulating coal inventories ahead of anticipated price increases, we believe the group is well positioned to cushion the impact of rising coal costs in the near term, particularly in 1QFY27.
- Investing in structural cost efficiencies. HUME is currently integrating a waste heat recovery (WHR) system into its cement manufacturing operations, which is expected to generate electricity cost savings of approximately RM2m per month upon commissioning. The RM100m project is slated for completion in Sep 27 (1QFY28), and is expected to help mitigate the impact of current energy cost headwinds from elevated fuel prices. We believe the WHR initiative will further underpin HUME's margin expansion trajectory while enhancing its cost resilience, reinforcing its position as one of the sector's highest-margin players (FY28 net margin: 22%).
Highlights
- While bulk cement ASPs have modestly normalised from the Nov 25 price adjustments (<10%), HUME continues to demonstrate margin resilience.
- The group remains well-equipped to manage cost headwinds, underpinned by: a) its disciplined coal procurement strategy, b) ongoing operational efficiency initiatives, and c) an agile manufacturing mix.
- HUME trades at an undemanding 7.5x FY27F PE (-1SD from industry mean), and offers attractive dividend yields of 5.4% and 5.7% over FY27-28. Maintain BUY with a target price of RM4.16.
Analysis
- Well-positioned to navigate elevated coal prices. The cement sector’s share prices have retraced by approximately 26% ytd, largely reflecting the sharp rise in Newcastle coal prices (+42% ytd) and Indonesian coal benchmark prices (+43% ytd). While coal typically represents a significant portion of Hume Cement Industries’ (HUME) COGS, the group remains well-equipped to manage cost headwinds, underpinned by: a) its disciplined coal procurement strategy; b) ongoing operational efficiency initiatives; and c) an agile manufacturing mix, prioritising production of high demand products.
- Solid coal procurement strategy. HUME's fuel cost resilience is underpinned by its advanced technology which enables utilisation of lower-grade coal without compromising product quality. The aforementioned coal generally trades at a discount to Newcastle benchmark coal, enabling the group to benefit from cost advantage. Coupled with HUME's strategy of accumulating coal inventories ahead of anticipated price increases, we believe the group is well positioned to cushion the impact of rising coal costs in the near term, particularly in 1QFY27.
- Investing in structural cost efficiencies. HUME is currently integrating a waste heat recovery (WHR) system into its cement manufacturing operations, which is expected to generate electricity cost savings of approximately RM2m per month upon commissioning. The RM100m project is slated for completion in Sep 27 (1QFY28), and is expected to help mitigate the impact of current energy cost headwinds from elevated fuel prices. We believe the WHR initiative will further underpin HUME's margin expansion trajectory while enhancing its cost resilience, reinforcing its position as one of the sector's highest-margin players (FY28 net margin: 22%).
BUY (Maintained)
Current price:
Target price:
Upside:
RM2.57
RM4.16
+61.9%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

17 Sept 2026
CapitaLand Malaysia Trust (CLMT MK): Robust Enquiries For i-TechValley Assets

28 Sept 2026
Uzma Group (UZMA MK) : Uzma Ver 4.0: Embracing Resilience In Growth

25 Sept 2026
Eco World Development (ECW MK): 3QFY26: In Line; Poised To Achieve Record Sales
Our latest research

12 Oct 2026
HE Group (HEGROUP MK): A Diversified MEP Player; Scaling Up On DC And Semiconductor Demand

8 Oct 2026
Northern Solar (NORTHERN MK): Wins Another LSS5 EPCC Award; Underpins Earnings Visibility

7 Oct 2026