BUY (Upgraded)
Current price:
Target price:
Upside:
Previous TP :
RM7.83
RM8.60
+10.0%
RM7.50
Analyst
Highlights
- We came away from a recent management meeting more sanguine on TM’s near-term prospects. 2027 earnings will be driven by: a) the absence of one-off manpower VSS cost, b) RM100m-150m in savings from 5G wholesale fees, and c) a strong TM Global project pipeline, including built-up DCs.
- The TM-Nxera 200MW fit-out is expected to start soon, and we value this DC project at RM1.30/share. By 2030, TM aims to build out 1GW of DC capacity, beyond the Johor cluster as demand moves into the Klang Valley/East Coast region. TM is also set to benefit from Malaysia’s sovereign cloud ambition.
- Upgrade from HOLD to BUY with a higher DCF-based target price of RM8.60, capturing TM-Nxera’s full valuation. Active capital management will provide a total shareholder return of 15%.
Analysis
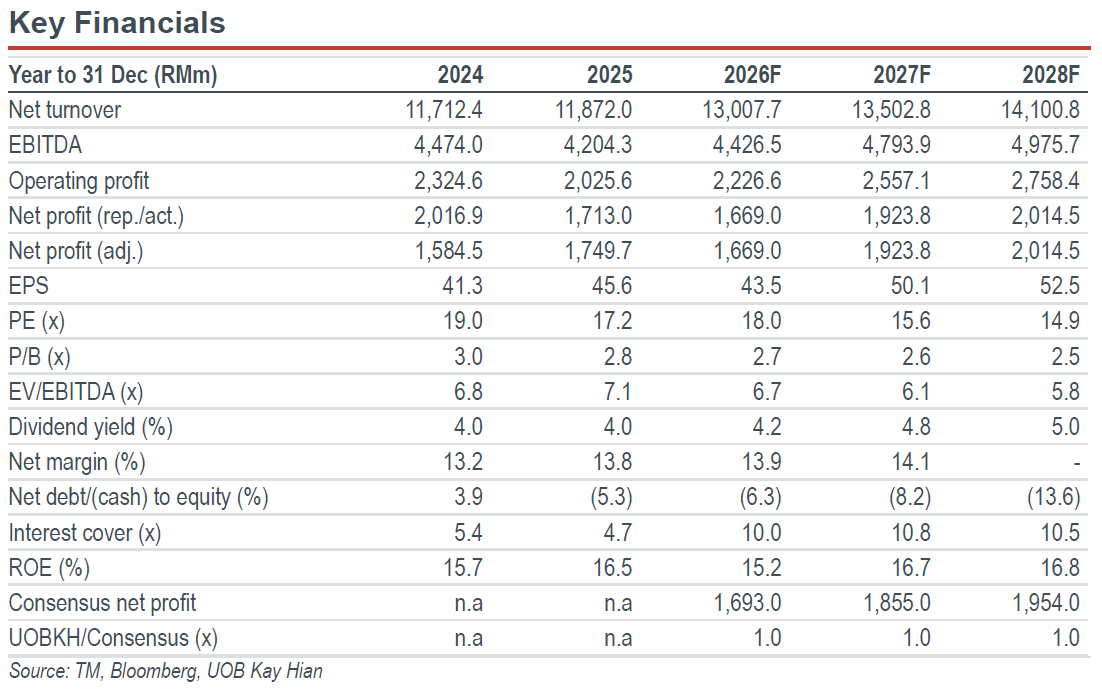
- On stronger footing in 2027. We came away from a recent management meeting more sanguine on Telekom Malaysia’s (TM) near-term prospects. We believe the group can achieve a robust 15% yoy earnings growth in 2027, on the back of a 1.5ppt EBITDA margin uplift to 3.5.5%. This reflects: a) the absence of the voluntary separation scheme (VSS) costs – the programme was launched in 2025; b) RM100m-150m in savings from 5G wholesale fees, given that TM has moved to U Mobile’s pay-per-use 5G wholesale contract as of 31 Jul 26; and c) a strong TM Global project pipeline, with submarine cable and data centres (DC) operating at close to full capacity.
- Robust underlying TM Global expansion. In 1H26, TM Global’s revenue rose the fastest, expanding 7% yoy to RM1.6b and accounting for 27% of group revenue. Key drivers included demand for DC capacity, international data and 5G backhaul services. We understand that TM will focus on two segments of expansion within the infrastructure business: a) DC – likely focusing in areas outside of the Johor cluster; and b) 10 submarine cables in the next two years.
Highlights
- We came away from a recent management meeting more sanguine on TM’s near-term prospects. 2027 earnings will be driven by: a) the absence of one-off manpower VSS cost, b) RM100m-150m in savings from 5G wholesale fees, and c) a strong TM Global project pipeline, including built-up DCs.
- The TM-Nxera 200MW fit-out is expected to start soon, and we value this DC project at RM1.30/share. By 2030, TM aims to build out 1GW of DC capacity, beyond the Johor cluster as demand moves into the Klang Valley/East Coast region. TM is also set to benefit from Malaysia’s sovereign cloud ambition.
- Upgrade from HOLD to BUY with a higher DCF-based target price of RM8.60, capturing TM-Nxera’s full valuation. Active capital management will provide a total shareholder return of 15%.
Analysis
- On stronger footing in 2027. We came away from a recent management meeting more sanguine on Telekom Malaysia’s (TM) near-term prospects. We believe the group can achieve a robust 15% yoy earnings growth in 2027, on the back of a 1.5ppt EBITDA margin uplift to 3.5.5%. This reflects: a) the absence of the voluntary separation scheme (VSS) costs – the programme was launched in 2025; b) RM100m-150m in savings from 5G wholesale fees, given that TM has moved to U Mobile’s pay-per-use 5G wholesale contract as of 31 Jul 26; and c) a strong TM Global project pipeline, with submarine cable and data centres (DC) operating at close to full capacity.
- Robust underlying TM Global expansion. In 1H26, TM Global’s revenue rose the fastest, expanding 7% yoy to RM1.6b and accounting for 27% of group revenue. Key drivers included demand for DC capacity, international data and 5G backhaul services. We understand that TM will focus on two segments of expansion within the infrastructure business: a) DC – likely focusing in areas outside of the Johor cluster; and b) 10 submarine cables in the next two years.
BUY (Upgraded)
Current price:
Target price:
Upside:
Previous TP :
RM7.83
RM8.60
+10.0%
RM7.50
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

24 Sept 2026
Sunway Construction (SCGB MK): Retracement Offers Opportunities; Upgrade To BUY

21 Sept 2026
Northern Solar (NORTHERN MK): All Cylinders Fired Up

8 Oct 2026
Northern Solar (NORTHERN MK): Wins Another LSS5 EPCC Award; Underpins Earnings Visibility
Our latest research

12 Oct 2026
HE Group (HEGROUP MK): A Diversified MEP Player; Scaling Up On DC And Semiconductor Demand

9 Oct 2026
Hume Cement Industries (HUME MK): Business Resilience Continues To Cement Its Margin Leadership
8 Oct 2026