Company Coverage
Telekom Malaysia (T MK): 2Q26: In Line; Underlying Net Profit Rises 5% yoy Given Revenue Flow Through
HOLD (Maintained)
Current price:
Target price:
Upside:
RM8.10
RM7.50
-7.4%
Analyst
Highlights
- 2Q26 core net profit (excluding Prihatin employee separation cost and forex
losses) rose 5% yoy but fell 7% qoq to RM406m. The sequential earnings
weakness was due to high content cost for the FIFA World Cup, booked in
Jun 26.
1H26 core net profit of RM843m is in line with expectations.
Maintain HOLD with a DCF-based target price of RM7.50.
Analysis
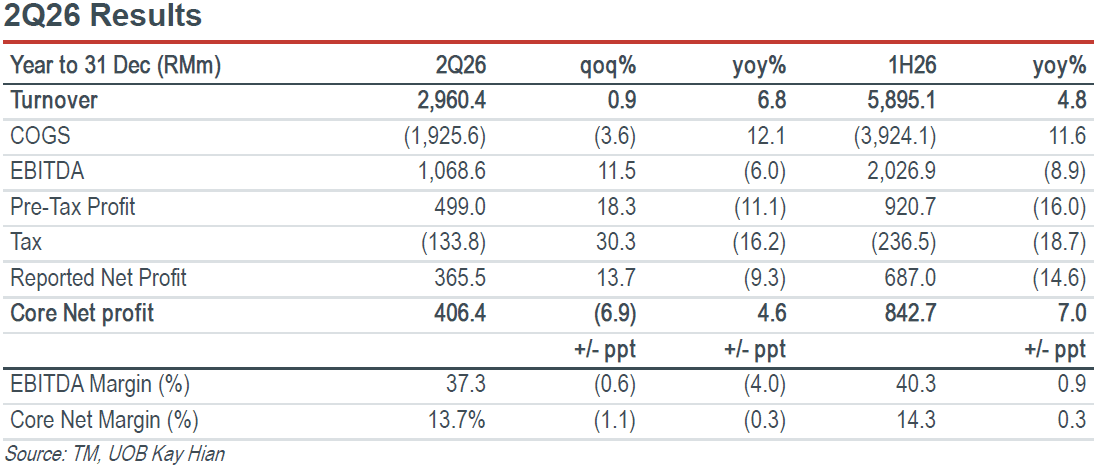
1H26 results within expectations. Telekom Malaysia’s (TM) 2Q26 core net
profit (excluding Prihatin employee separation cost and forex losses) rose
5% yoy but fell 7% qoq to RM406m. The sequential earnings weakness was
due to high content cost for the FIFA World Cup, booked in Jun 26. Another
portion of the content cost will be booked in Jul 26. 1H26 core net profit of
RM843m (+7% yoy) is in line with house and street’s expectations
Highlights
- 2Q26 core net profit (excluding Prihatin employee separation cost and forex
losses) rose 5% yoy but fell 7% qoq to RM406m. The sequential earnings
weakness was due to high content cost for the FIFA World Cup, booked in
Jun 26.
1H26 core net profit of RM843m is in line with expectations.
Maintain HOLD with a DCF-based target price of RM7.50.
Analysis
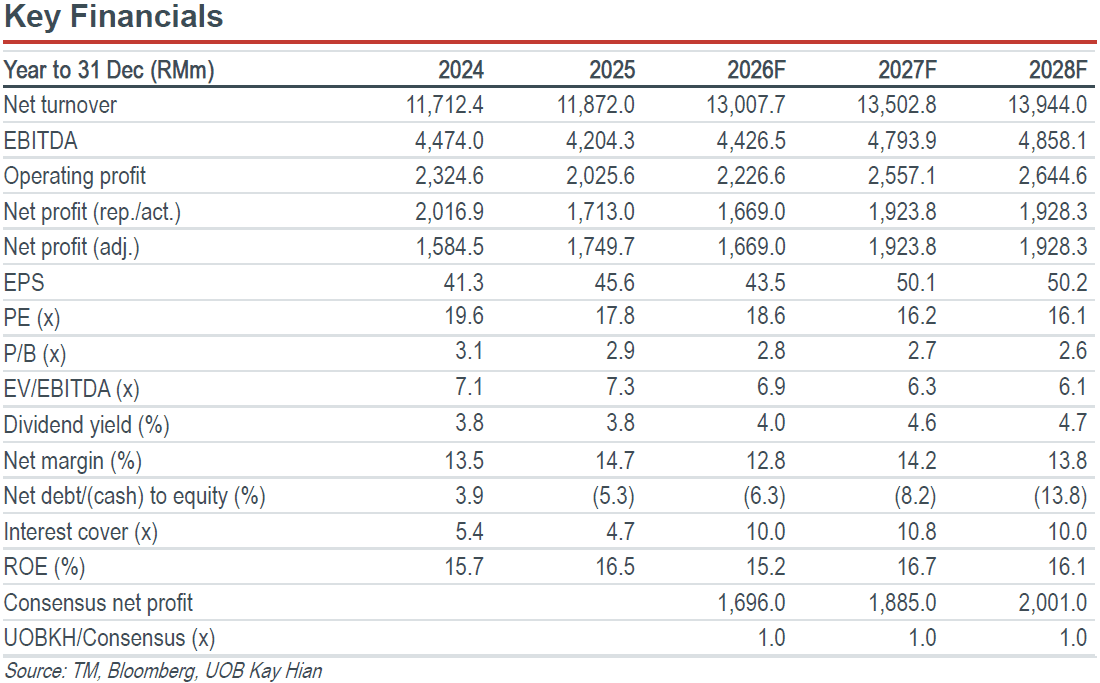
1H26 results within expectations. Telekom Malaysia’s (TM) 2Q26 core net
profit (excluding Prihatin employee separation cost and forex losses) rose
5% yoy but fell 7% qoq to RM406m. The sequential earnings weakness was
due to high content cost for the FIFA World Cup, booked in Jun 26. Another
portion of the content cost will be booked in Jul 26. 1H26 core net profit of
RM843m (+7% yoy) is in line with house and street’s expectations
HOLD (Maintained)
Current price:
Target price:
Upside:
RM8.10
RM7.50
-7.4%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Aug 2026
Tenaga Nasional (TNB MK): 2Q26: In Line; EBITDA Margin 29% On Higher Non-Fuel Opex

1 Sept 2026
Axiata Group (AXIATA MK): 2Q26: In Line; Partial Monetisation Of Edotco Remains A Key Catalyst

1 Sept 2026
CIMB Group (CIMB MK): 2Q26: Resilient Showing Despite Forex And NIM Headwinds
Our latest research

12 Oct 2026
HE Group (HEGROUP MK): A Diversified MEP Player; Scaling Up On DC And Semiconductor Demand

9 Oct 2026
Hume Cement Industries (HUME MK): Business Resilience Continues To Cement Its Margin Leadership

8 Oct 2026